Myntex Credit OS
Every piece you need to lend, in one system.
Credit core, decision engine, accounting and collections. Deployed by engineers who join your team and stay until you place your first loan.
Myntex DeployForward-deployed engineers, inside your team until your first disbursement- Identity verified
- Payment capacity within policy
- Reason recorded with the decision
- 01Risk
- 02Operations
- 03Core integration
Disbursement posted to portfolio
Same system, no reconciliation file
Proven in production
We run a real credit operation. We set up the same system for yours, and stay inside your team until you place your first loan.
Myntex builds and operates the technology behind Tafi, a consumer-credit platform in Panama. Built for Tafi and running there every day, it is configured for each operation that adopts it. If it fails, it fails us first.
Integrated in production · current and past
 WhatsApp

 Western Union
 Dynamics 365
 Azure
- 01ProofDone
- 02SetupDone
- 03ConnectDone
- 04First disbursementIn progress
Engineers stay until this line closes
Myntex Deploy · Forward-deployed engineering
We stay until your first disbursement.
Our engineers join your team and work inside your risk, operations and technology groups until you place your first loan. The sale doesn't end at signature.
Inside your team
Engineers work with your risk, operations and IT people, on your schedule and in your tools, as part of your team.
Your stack, your call
We integrate with the core banking, bureau, ERP and channels you keep, and help you retire the ones that cost more than they're worth.
Measured by your first loan
The engagement is judged by your first disbursement, then by your portfolio, every month.
The knowledge stays with you
Credit policies, scoring rules and runbooks are documented and handed over. Your team stays in control after we step back.
Inside Myntex Credit OS
One loan, station by station.
Each station on the line is a module of Myntex Credit OS doing one job, in order. Watch one application move through; every result it carries is recorded on the way.
Inside Myntex Credit OS
One loan, station by station.
Each station on the line is a module of Myntex Credit OS doing one job, in order. Watch one application move through; every result it carries is recorded on the way.
Every payment lands where it belongs
Payments come in from every channel at once. Each one's unique code is read and matched to its loan, then applied to the next installment due, in order, and posted to the ledger with its trace. A payment that arrives twice is recognised and set aside.
5 of 12 applied · next due: 6 · 0 unmatched
Myntex Credit OS
The whole credit lifecycle, in one system.
The policies, the scoring and the controls arrive configured. You decide who you lend to and how much.
Credit Core
Where your installment credit products, customers and portfolio live.
- Installment products and terms
- Customers and accounts
- Loan state machine
Decision Engine
You define who you lend to and how much, with versioned credit policies and interpretable points-based scoring. Every decision keeps its reason.
- Versioned credit policies
- Points-based scoring
- The reason behind every decision
Accounting
Every portfolio movement is posted to a double-entry ledger inside the same system.
- Double-entry ledger
- Event-sourced postings
- Audit trail
Collections
Installment collection runs inside the same operation and posts to the same ledger.
- A unique code for every payment
- Per-payment reconciliation status
- Late charges configured per product
Channels
Any front end connects through the API. Point of Sale and Conversational channels come ready, with WhatsApp first.
- Any front end via API
- Point of Sale
- Conversational, WhatsApp first
Identity & Compliance
The platform layer every module relies on to know who is applying.
- KYC and KYB
- AML checks
- PEP screening and list ingestion
Conversational credit
The whole loan, inside the conversation.
Onboarding, decision, acceptance, signature, servicing and collections run in a WhatsApp conversation at Tafi every day. The chat is a front end: the credit logic stays in Myntex Credit OS, so the same operations are available by API to your app, website or branch systems.
- 01Identity · KYC
- 02Decision · plan simulation
- 03Acceptance · OTP
- 04E-signature
- 05Collections · day −3
 WhatsApp· Illustrative
- Today
Hi, I'd like to pay for this in installments.10:14
- Identity · KYC
Happy to help. First, send a photo of the front and back of your ID.10:16
ID, front and back10:18
- Decision · plan simulation
You're approved. Choose the plan that suits you.10:20
3 installments6 installments12 installments 6 installments10:22
- Acceptance · OTP
To accept, enter the code we just sent you by SMS.10:24
4 8 2 110:26
- E-signaturePDFPromissory note.pdfPDF · signed
10:28
- Monday
- Collections · day −3
Reminder: installment 2 is due in 3 days.09:00
Pay now
Originate in the chat
- Identity checks with ID photos
- Installment plan simulation
- Acceptance of terms by OTP, with resend
- Security question as a fallback factor
- E-signed promissory note
Service and collect
- Loan status, account and payments in the chat
- Reminders by days past due: before the due date, on it, and in stages after
- WhatsApp, SMS and email, with delivery and read tracking
- Unique payment codes that reconcile to the loan
Under the hood
- A dedicated API surface for onboarding, credit, collections, account and wallet
- The bot runs at the messaging provider; the credit logic stays in the core
- One-time codes by SMS, voice call, email or WhatsApp
- The same operations, by API, for your own app or website
Modernize on your terms
Keep what works. Retire what costs too much.
Start with the piece that costs you most, whether that's a core licence, a decision engine or manual reconciliation, and keep everything else running. Every module is exposed through APIs and events, so you replace on your own schedule.
- 01
Replace the most expensive piece first
Swap out the loan-core licence, the decision-engine fees or the manual reconciliation that costs you most, while the rest of your stack keeps running.
- 02
Consolidate
Run core, decisioning, accounting, collections and identity checks on one platform, instead of separate vendors and the integrations between them.
- 03
Run the full Credit OS
Retire the legacy platform completely when you're ready, and launch every new credit product by configuration.
Your stack · stays only where it earns its keep
- Core banking
- Credit bureau
- ERP / general ledger
- Your app, web and branch
Myntex Credit OS · add what you need
- Credit Core
- Decision Engine
- Accounting
- Collections
- Identity & Compliance
Where the savings come from
Lower what it costs to run credit, every month.
Fewer licences
One platform replaces separate contracts for the loan core, the decision engine, collections and identity orchestration.
Changes by configuration
A new credit product, policy or bank reconciliation file is a setting your team changes, with no vendor project to pay for.
No manual reconciliation
Payments are applied to their installment automatically, duplicates are caught, and entries post straight to your ERP. The hours go back to your team.
A stack you control
No vendor roadmap or renewal cycle decides when you can launch, change a policy or move your data.
We did it ourselves
We built our credit core in three months, then moved Tafi's loan book onto it in two, existing loans included. You start from a platform already running in production.
Bring your vendor invoices. We'll map what Myntex replaces and what it costs you today.
Providers sit behind their own layer
The risk engine, identity and messaging providers each sit behind their own service layer. We switched KYC providers in production without locking anyone out mid-verification.
Accounting rules are configuration
Each business event maps to a journal in your ERP. Every line is checked for double-entry balance before it's posted, so nothing unbalanced reaches your books.
Every state change leaves as an event
Loan state changes are published as integration events through a durable outbox, so no change is lost between the ledger and your systems.
Compliance and risk
Compliance inside every credit flow, not after it.
Identity checks, AML screening, the customer risk matrix your regulator asks for and the credit policy all run on the same data as the loan. Every decision leaves a record your compliance team can follow.
Customer risk matrix
The risk matrix your regulator requires, kept current for every customer.
Panama's regulator expects a documented AML risk rating for each customer. Myntex scores every client on six factors from data the platform already holds, assigns a risk level, and builds the SBP client reports from the same model, instead of a spreadsheet rebuilt by hand each quarter.
SBP and compliance reports from the same model
- Active clients
- Active credit clients
- Active credit lines
- Cancelled credits
- Principal clients
- Pending customer profiles
Risk factors
LowMediumHigh
- IdentificationIdentity and nationality data
- ActivityProfession and labor situation
- ProductCredit products held and their payment status
- ChannelHow the customer was onboarded
- GeographyFATF high-risk jurisdiction flags
- PEP statusMatched against 16 PEP sources
Illustrative scores. Weights and level cut-offs follow each institution's approved methodology.
Risk levelMedium
Credit policy · versioned graph
- 01Eligibility gates
- 02Bureau read
- 03Composite score
- 04Risk-tier matrix
- 05Limit by verification
- 06Reason code
policy_id · version · release date
Risk-tier matrix
Verification quality →
Illustrative layout. Thresholds and tiers are set per institution.
KYC and KYB
Biometric KYC with a 1:1 face match against the enrolment selfie, and step-up re-verification before sensitive changes. Merchant onboarding runs as a 17-state flow with section-by-section human review and e-signed contracts.
- 1:1 face match
- Step-up verification
- Signed webhooks with replay protection
AML lists and PEP matching
24 official sources ingested with row-level lineage: OFAC, UK OFSI, EU and UN sanctions lists, Panama's UAF national list, FATF high-risk jurisdictions and 16 PEP sources. PEPs are matched deterministically in four tiers, tuned for precision over recall.
- 24 official sources
- Source hash, URL and load time per row
- Four-tier PEP matching
Credit risk policy
Credit policies are versioned graphs: eligibility gates, bureau read, composite score, a risk-tier matrix, a limit capped by verification quality, and a reason code. Each version is built and checked with assertions before it's released.
- Interpretable points-based score
- Risk-tier matrix
- Policy version on every decision
Audit trail
The credit core is event-sourced, so the exact state of any loan on any date can be replayed. Accounting enforces double entry with zero tolerance, and every merchant-onboarding step emits a domain event.
- Event-sourced ledger
- Zero-tolerance double entry
- Traceable consents
Measured in a restore drill: at most 5 minutes of data lost, back in service in 65 seconds.
How we work
We operate before we sell.
To close the distance between wanting to lend and being able to, we work in five ways.
Myntex Proof
Run the business before selling it
Proven on a real credit operation, with the method used to measure it. You don't start from zero.
- Proven on
- A real credit operation
- Method
- Documented and shared
- Starting point
- A working configuration
Running at Tafi
Built for Tafi. Running every day.
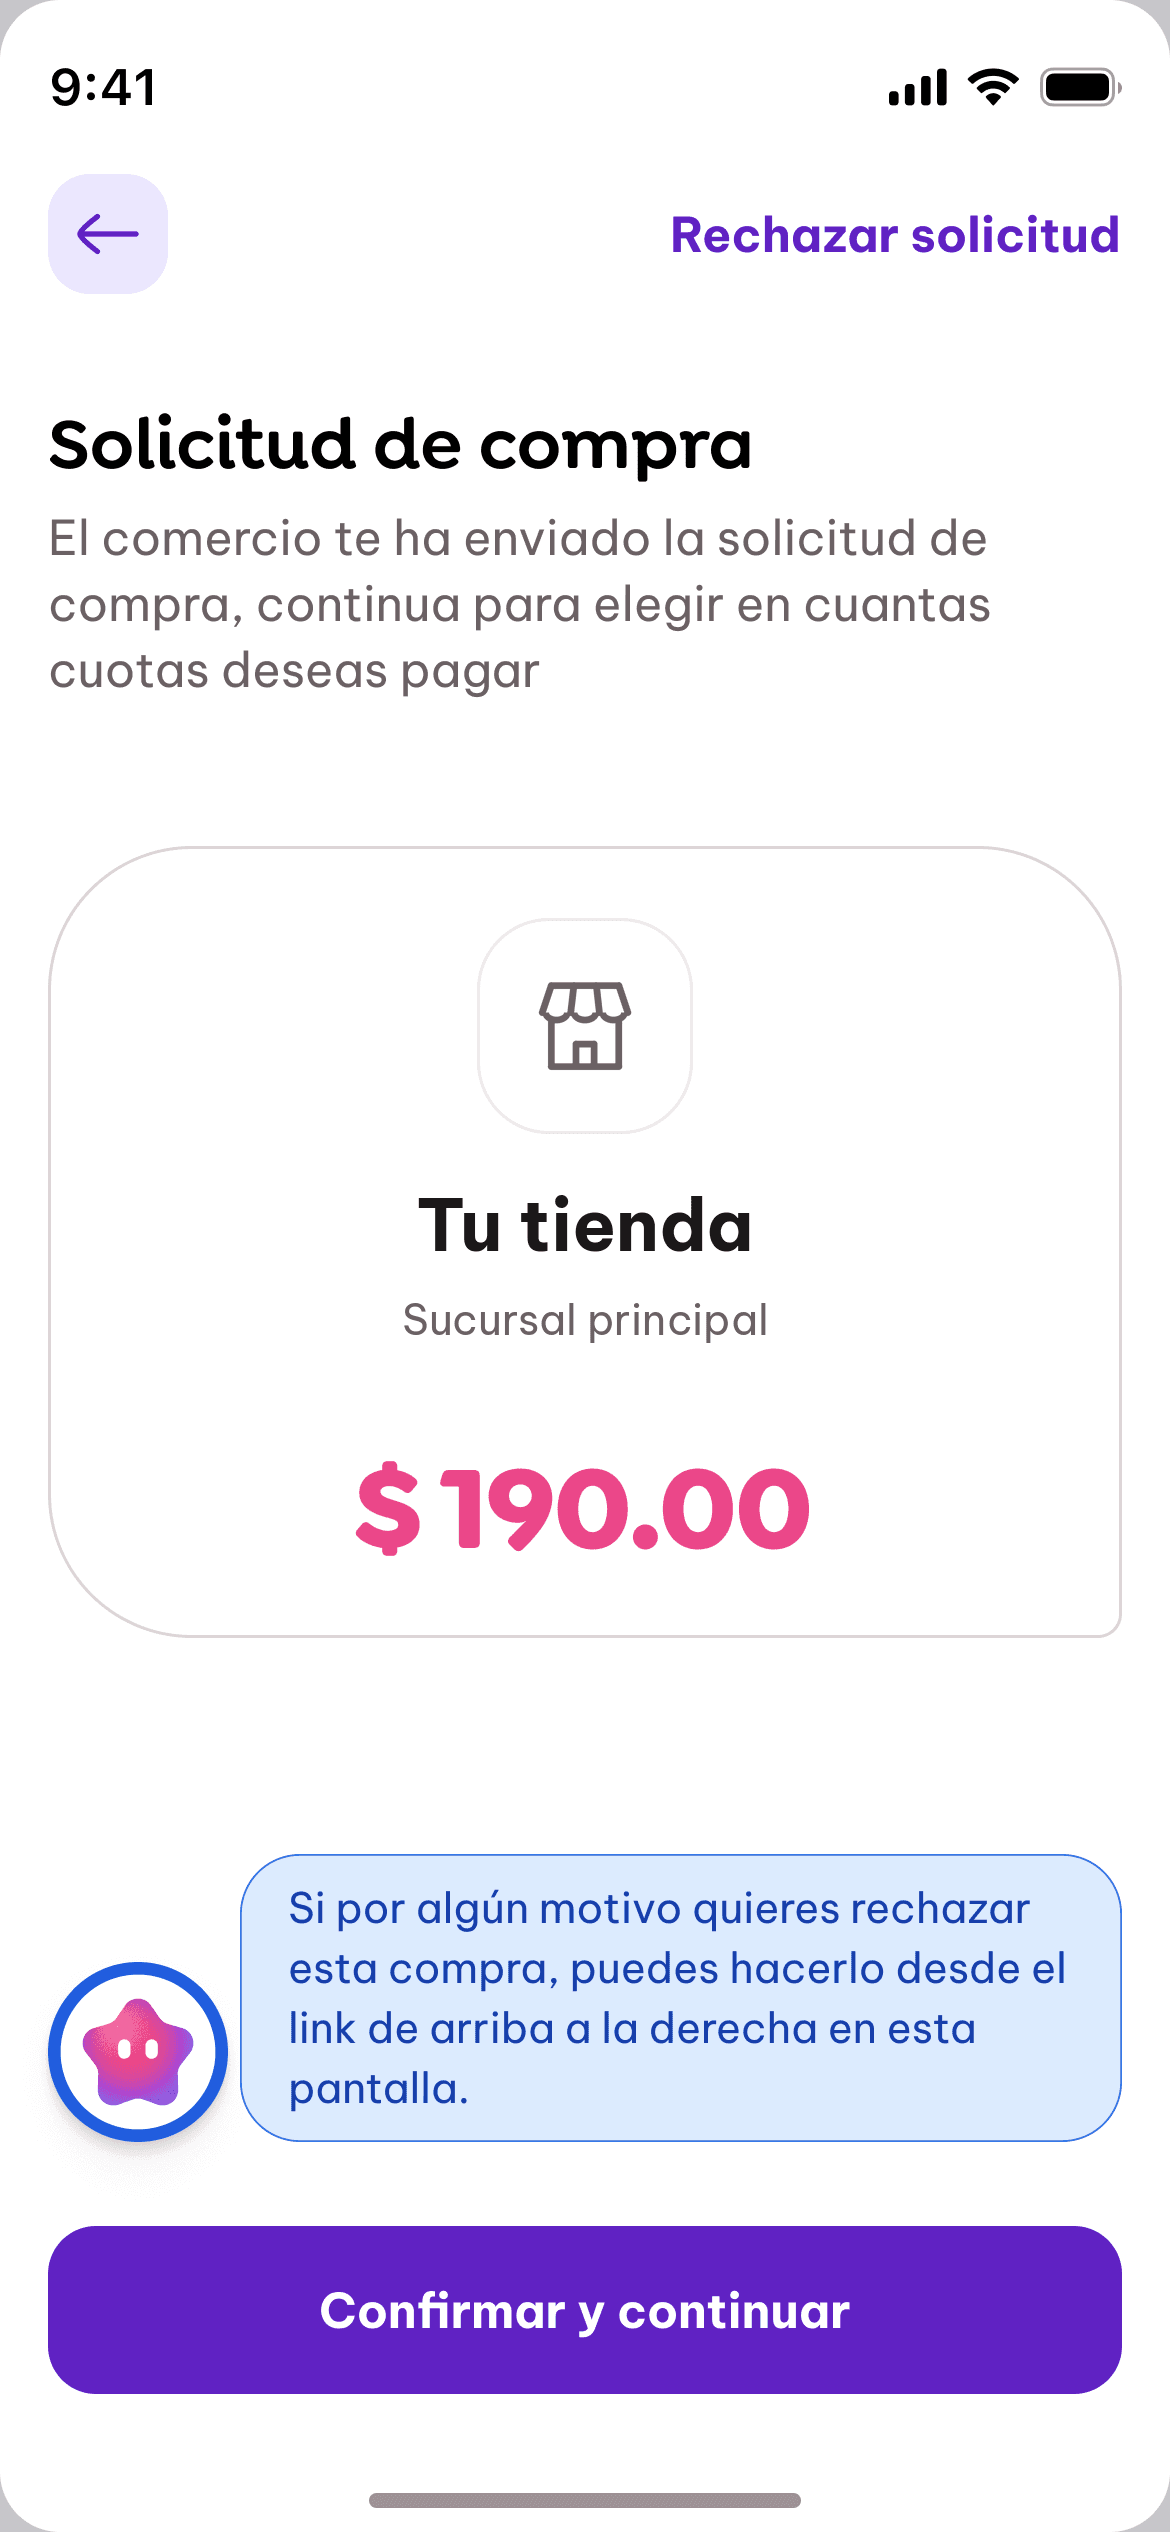
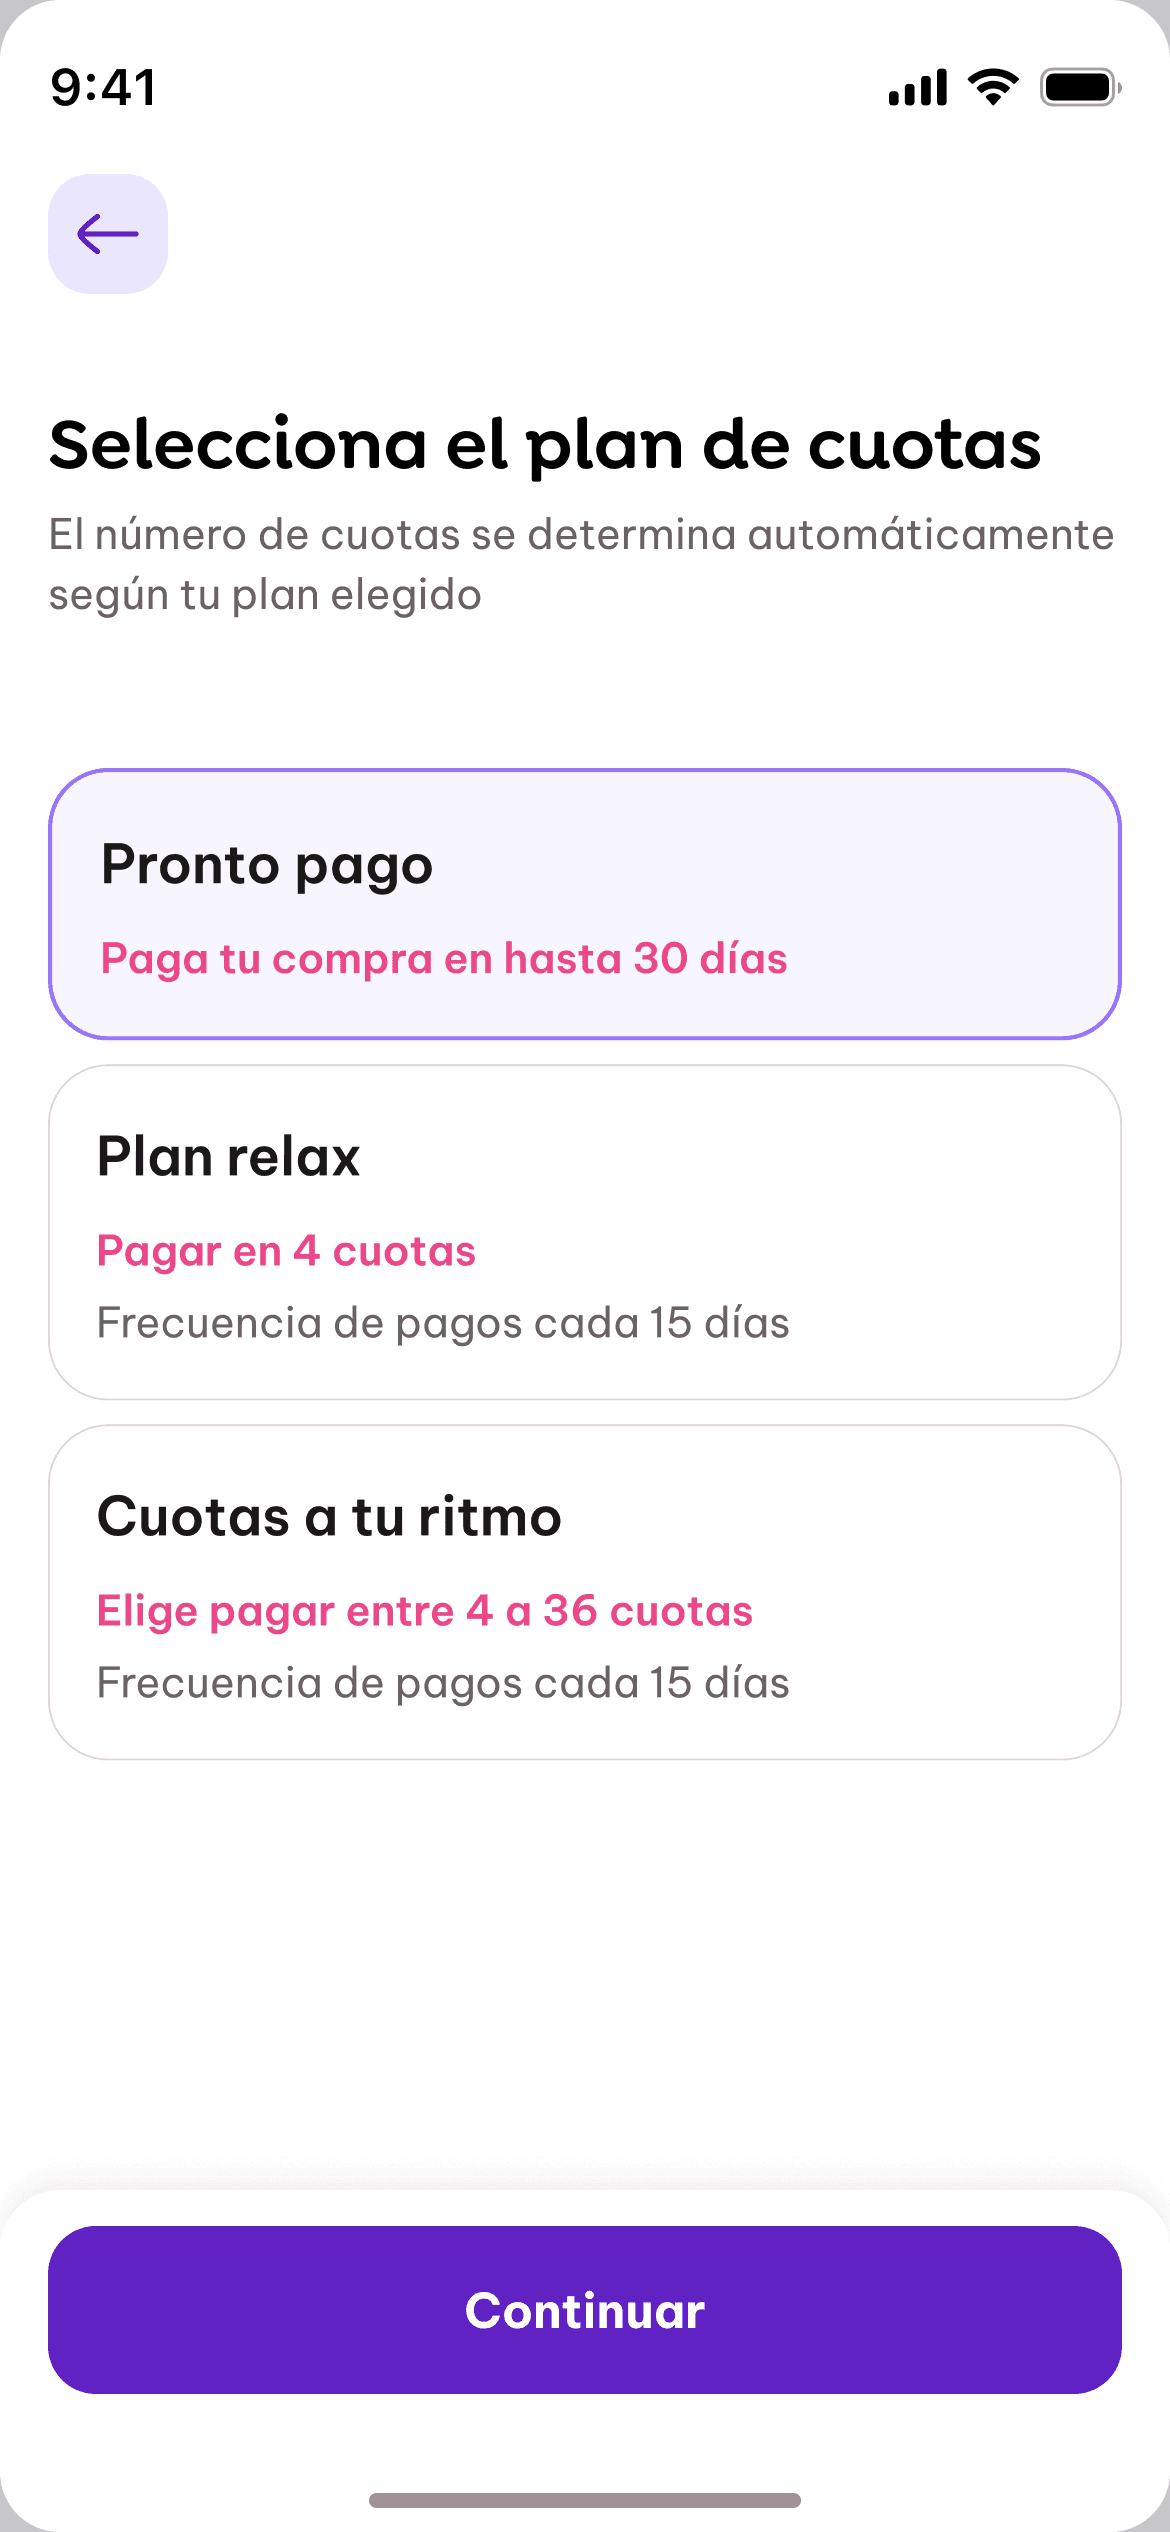
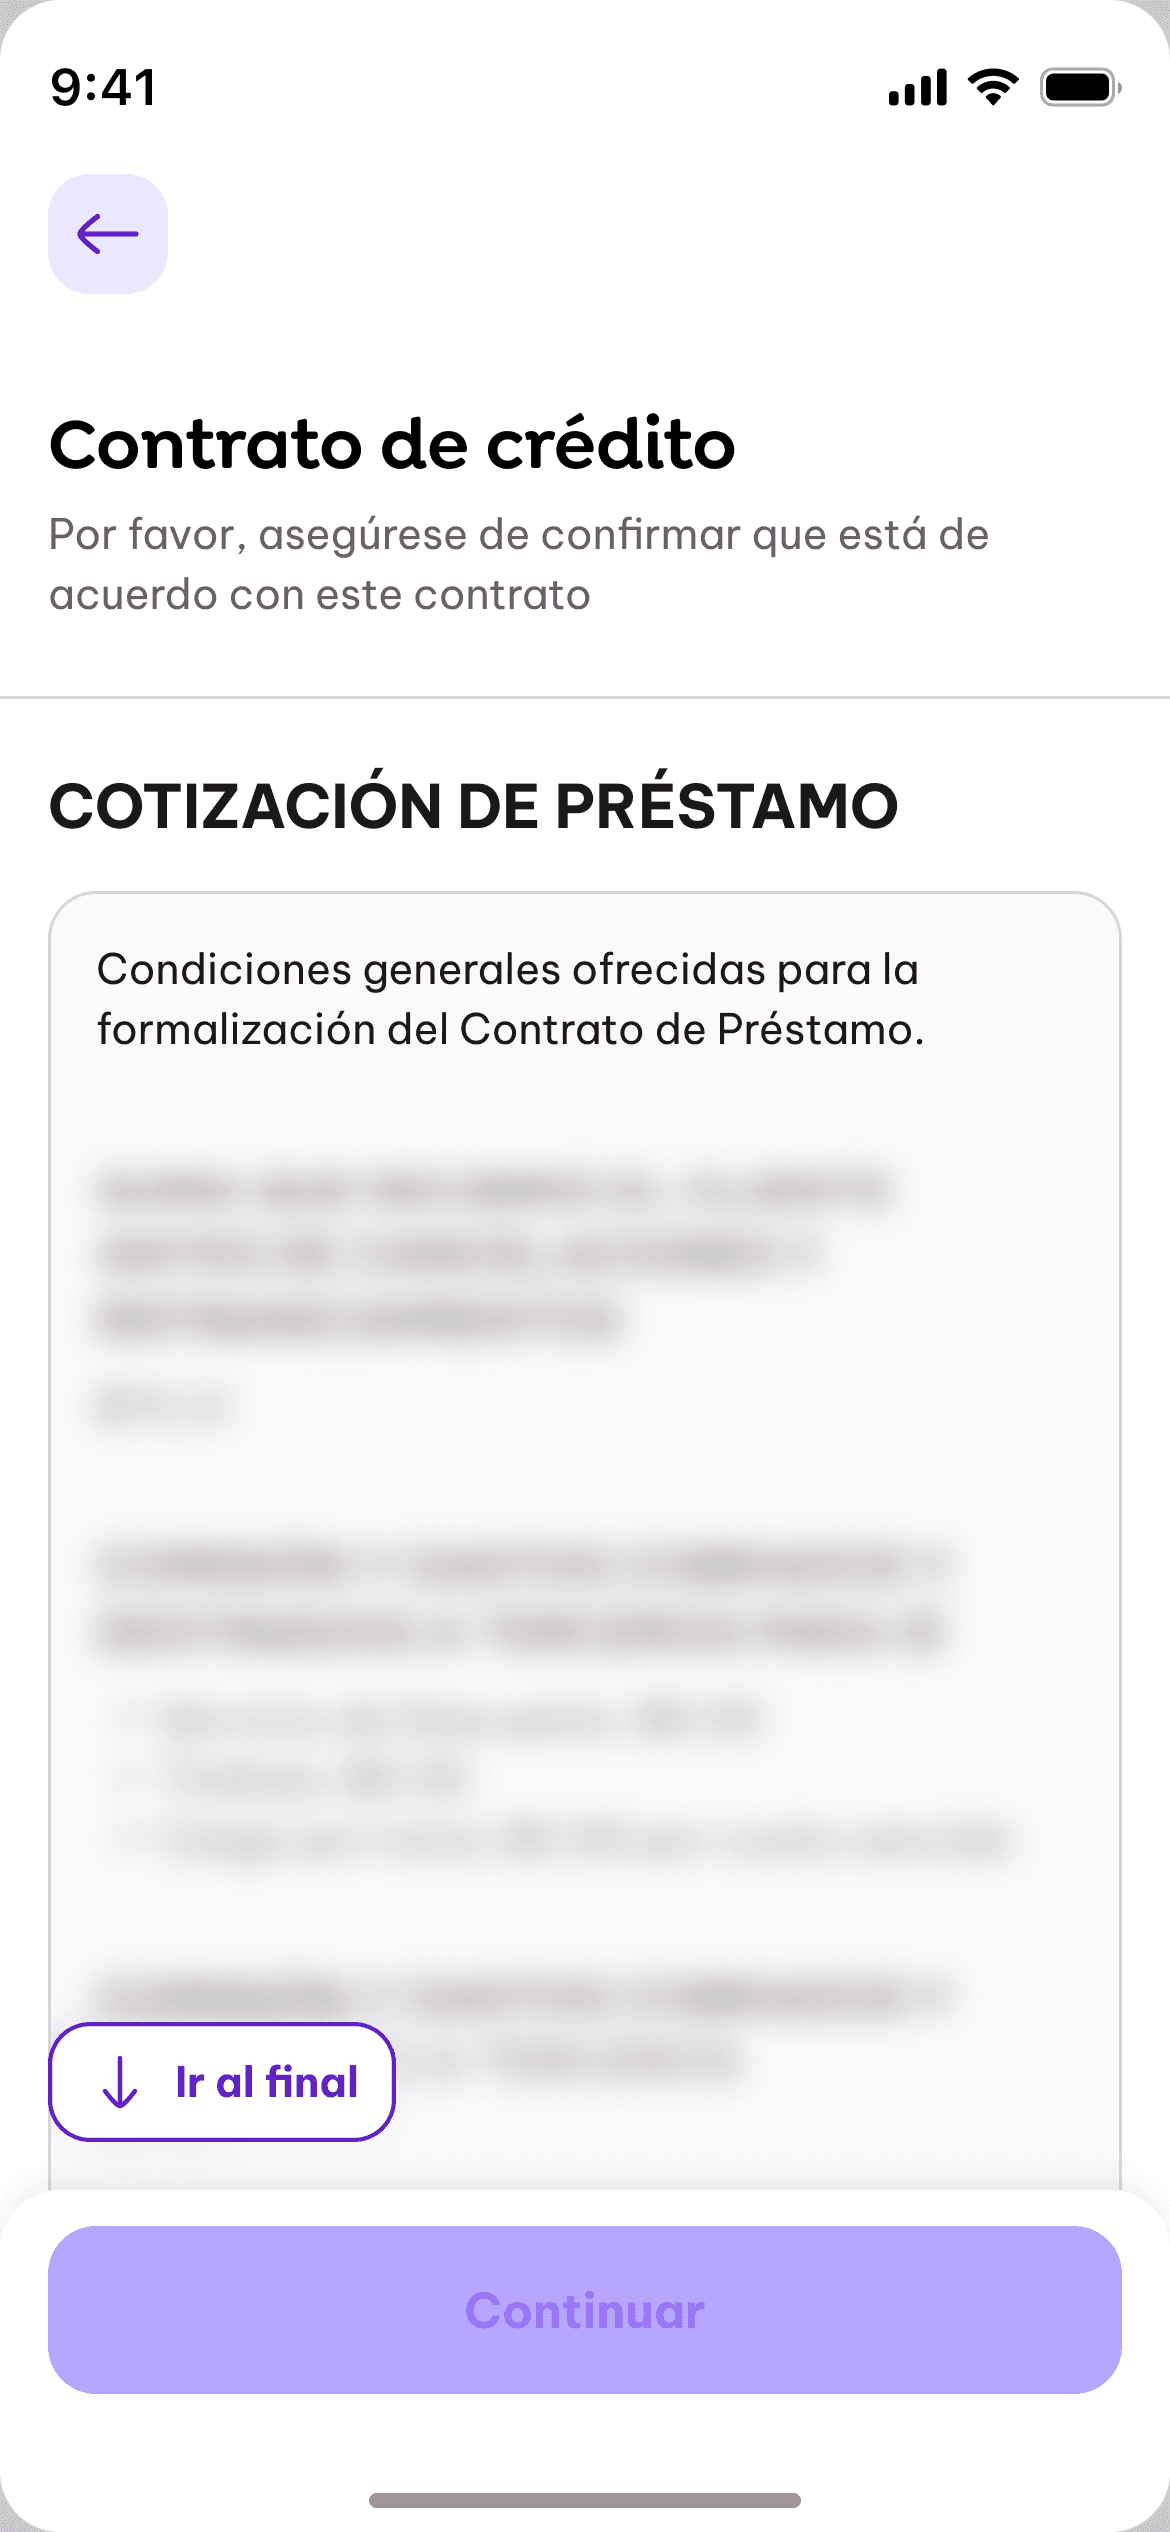
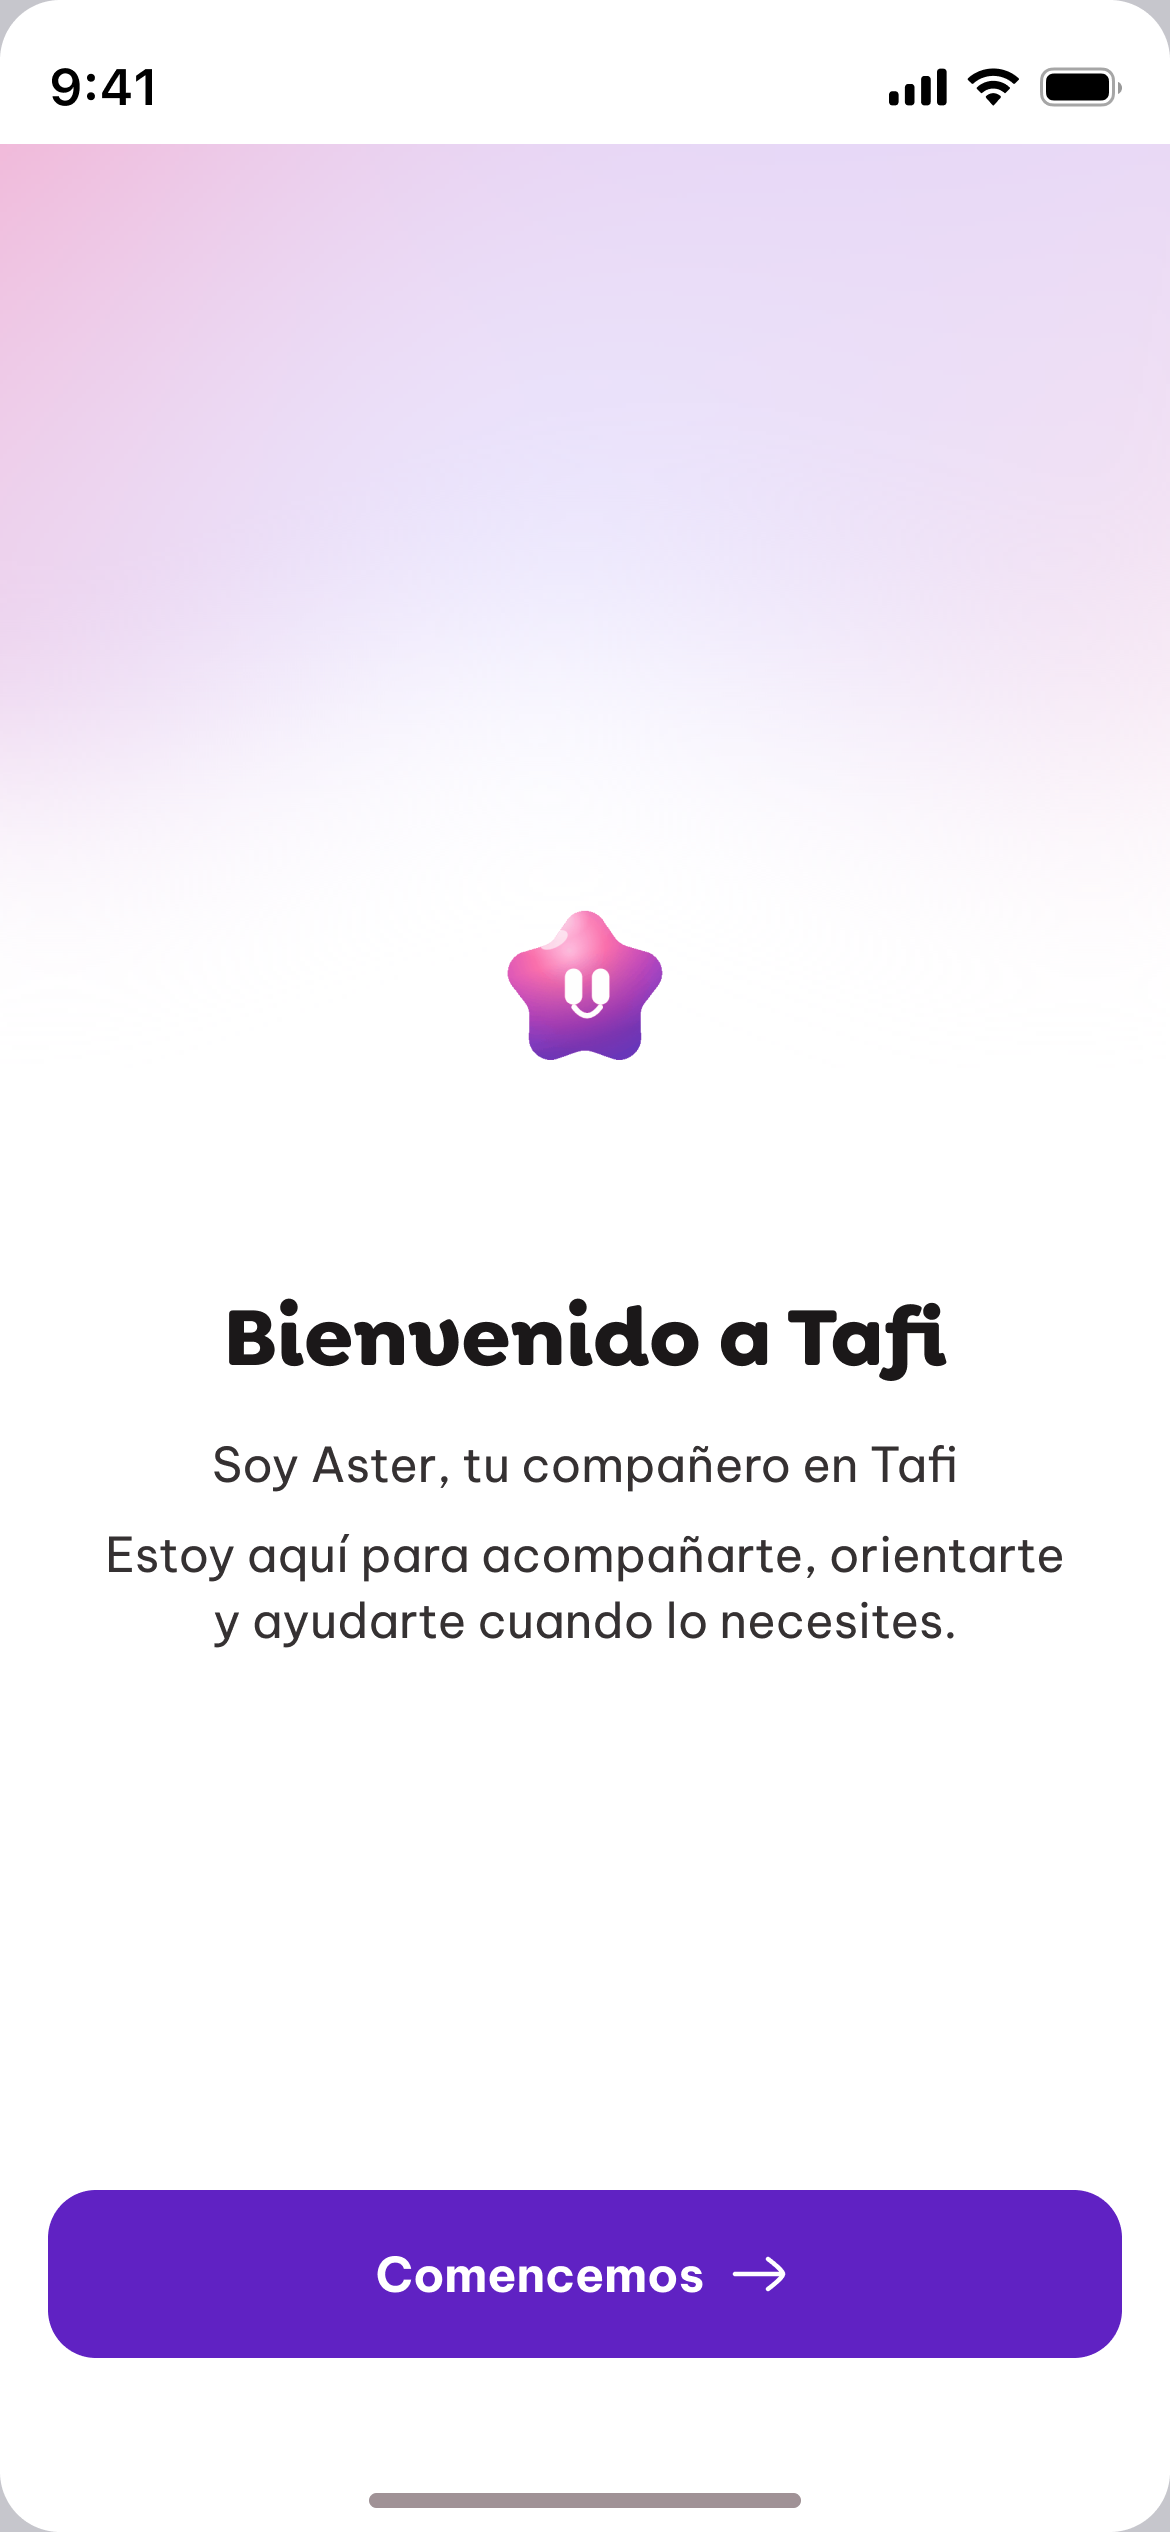
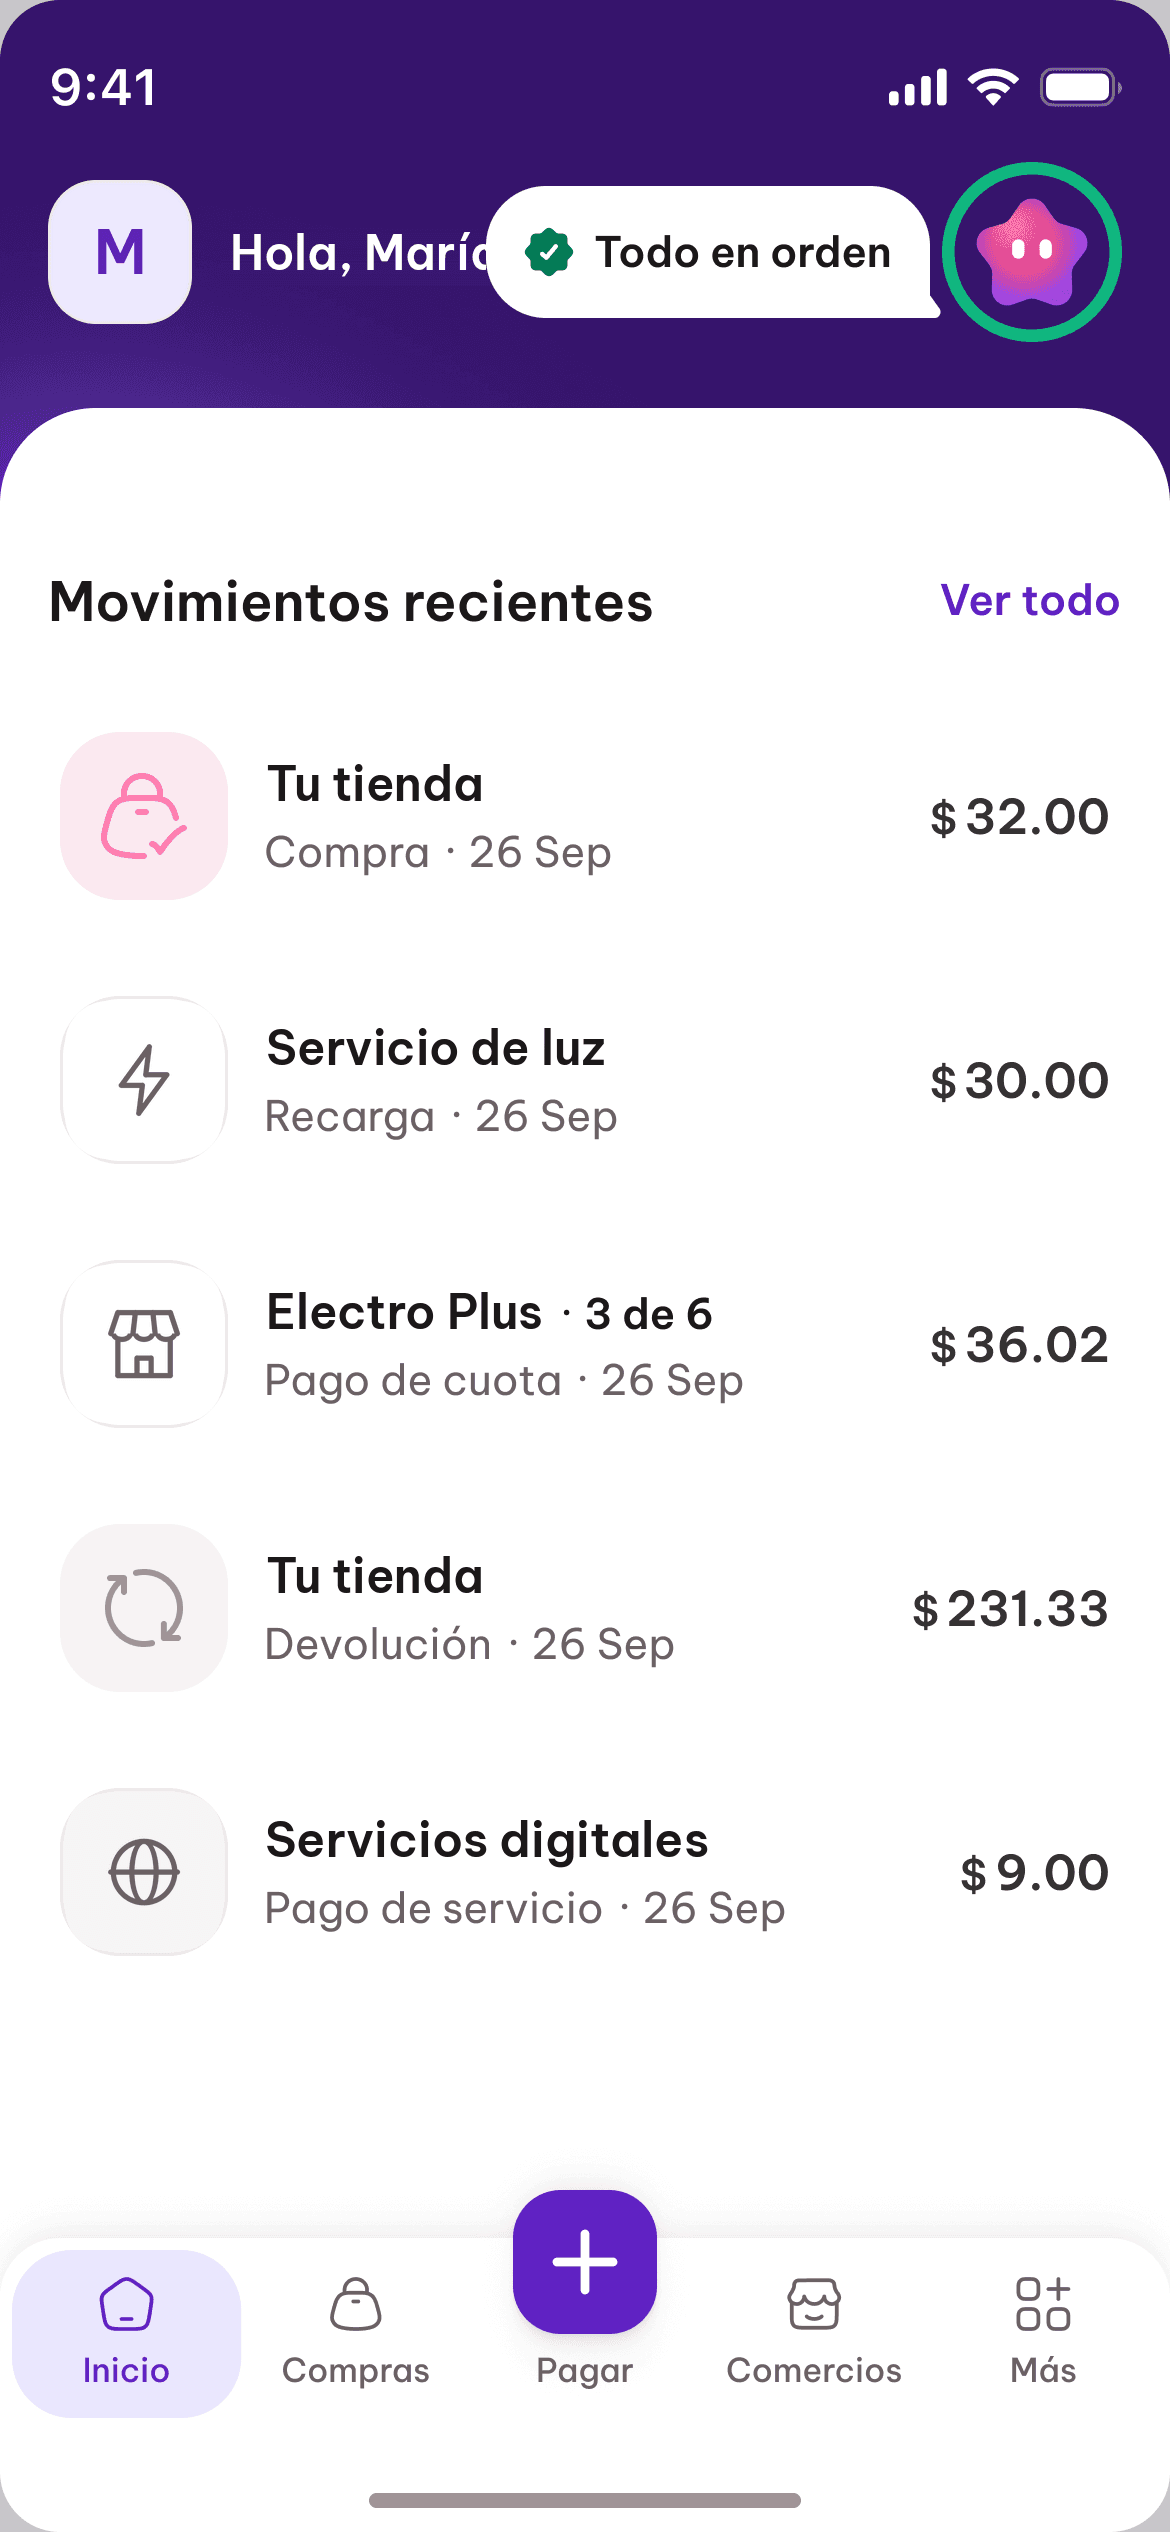
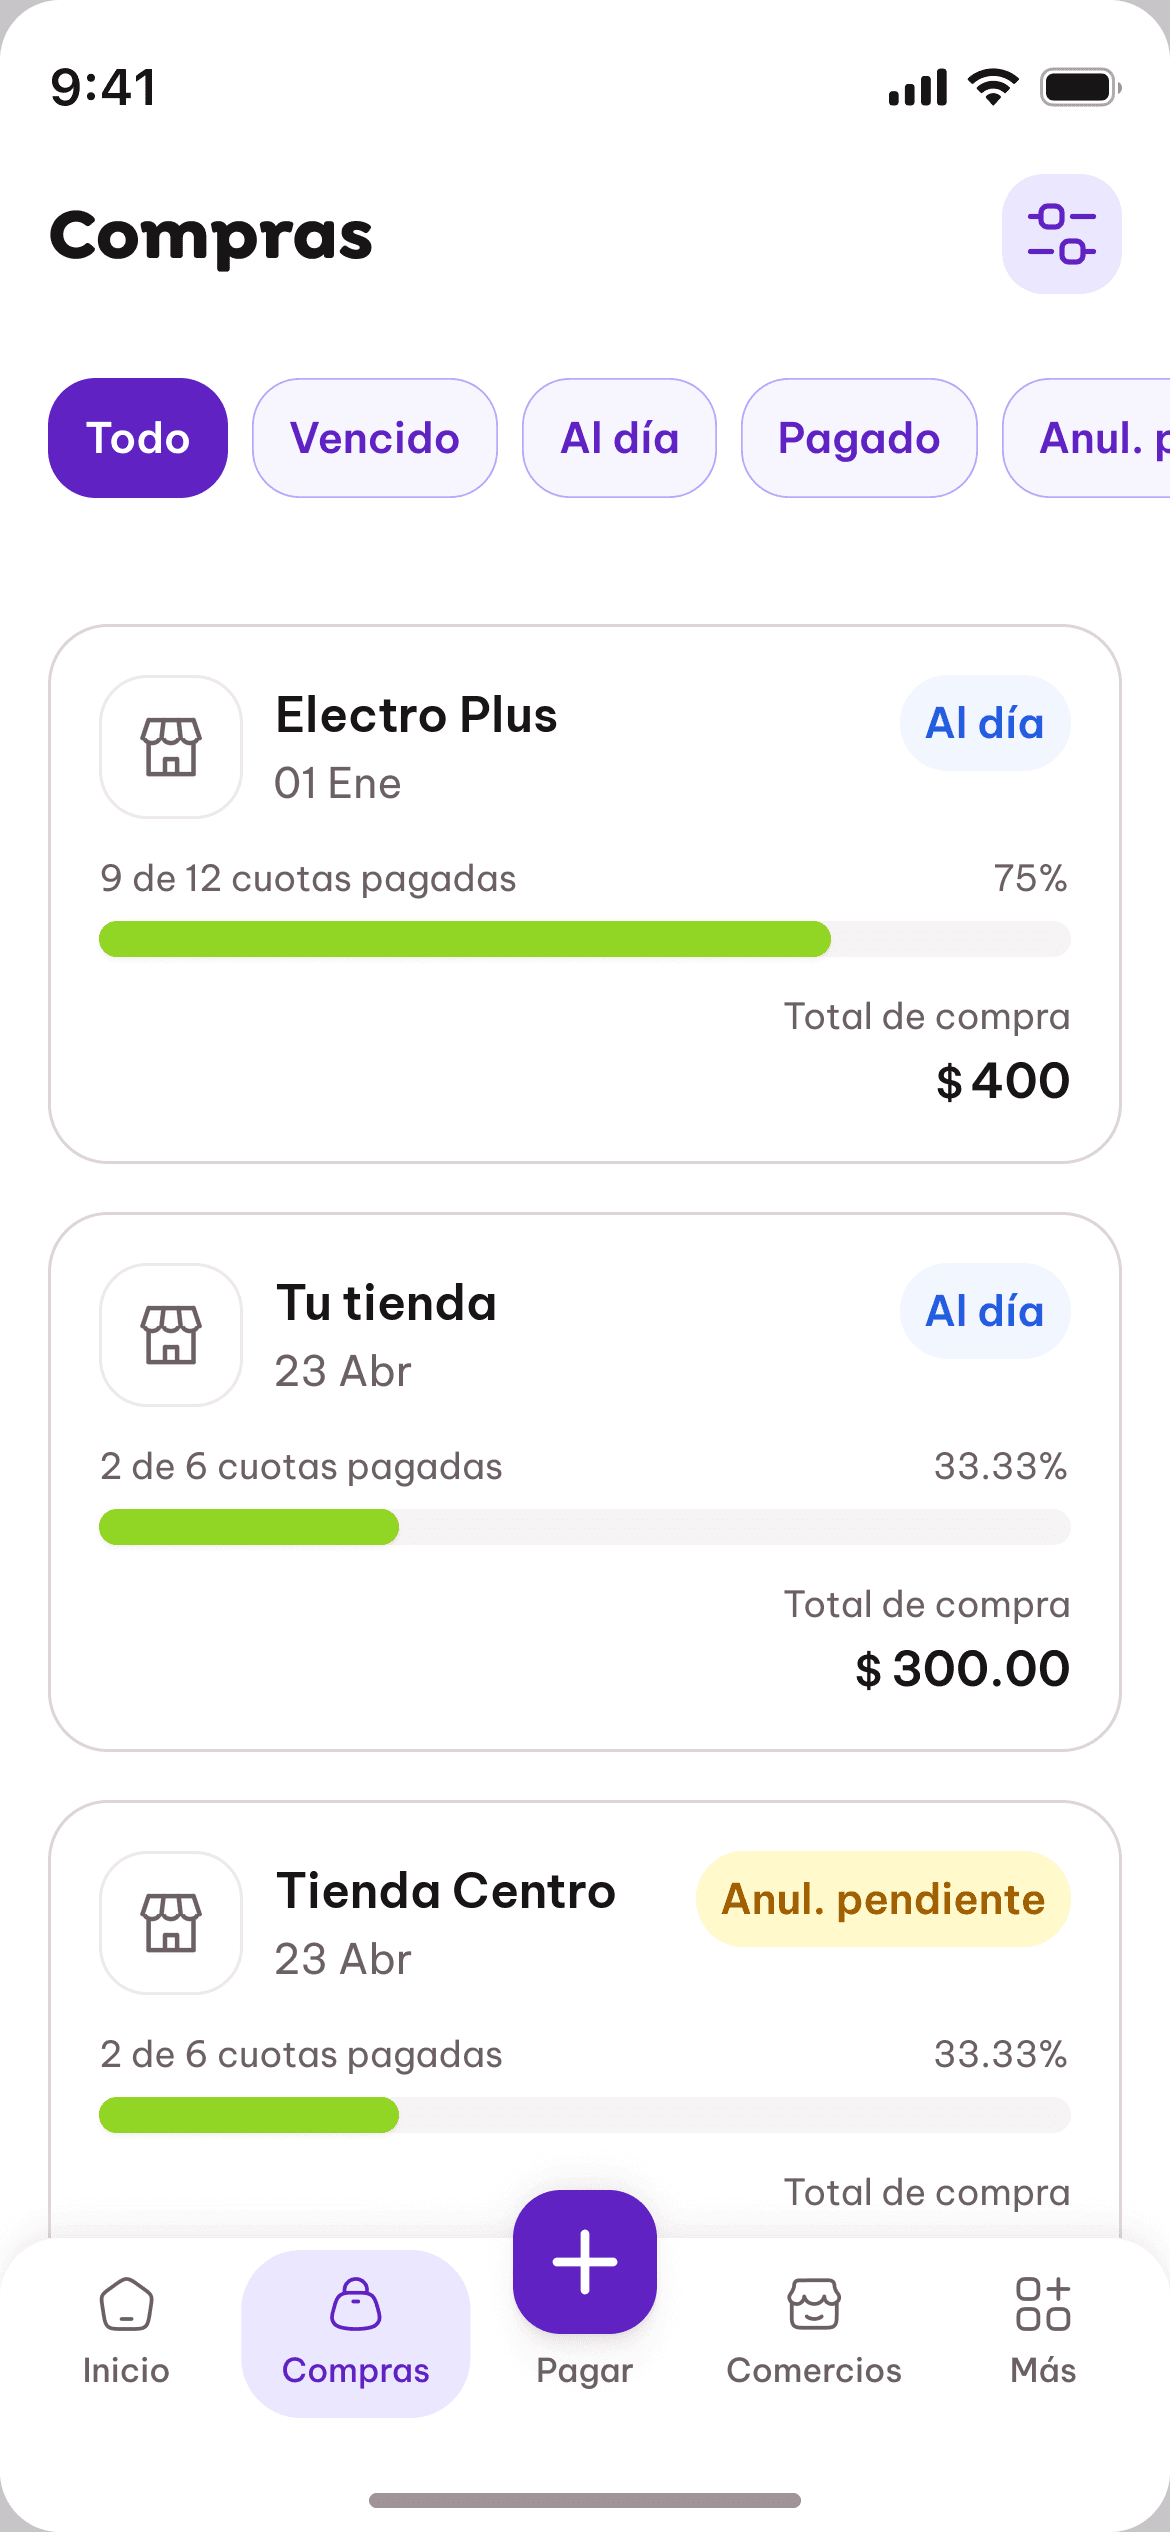
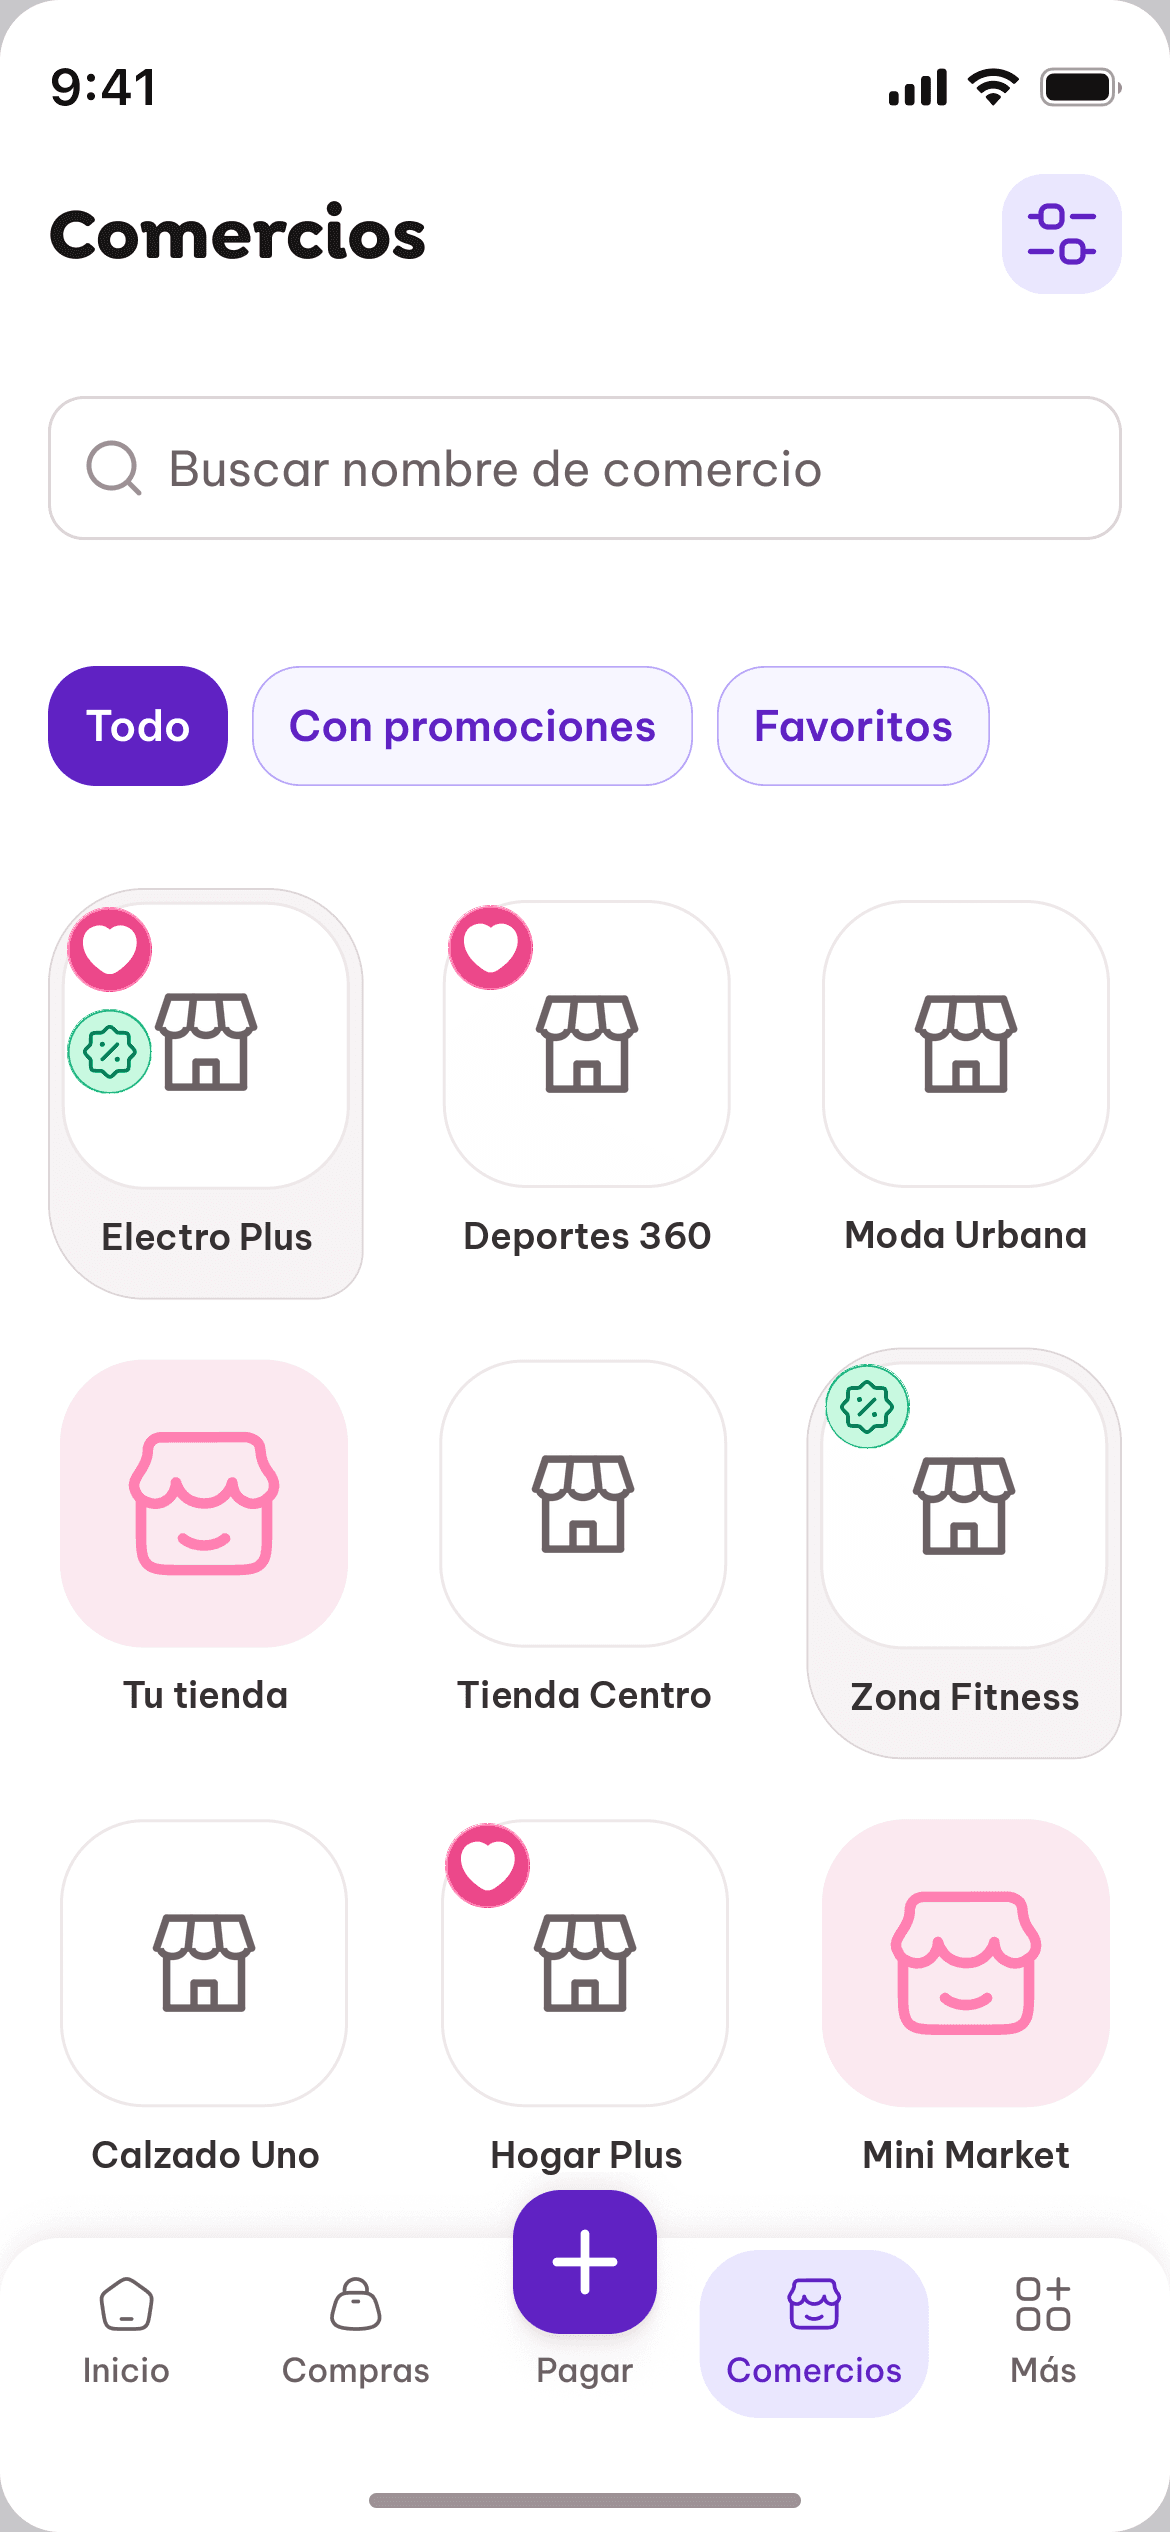
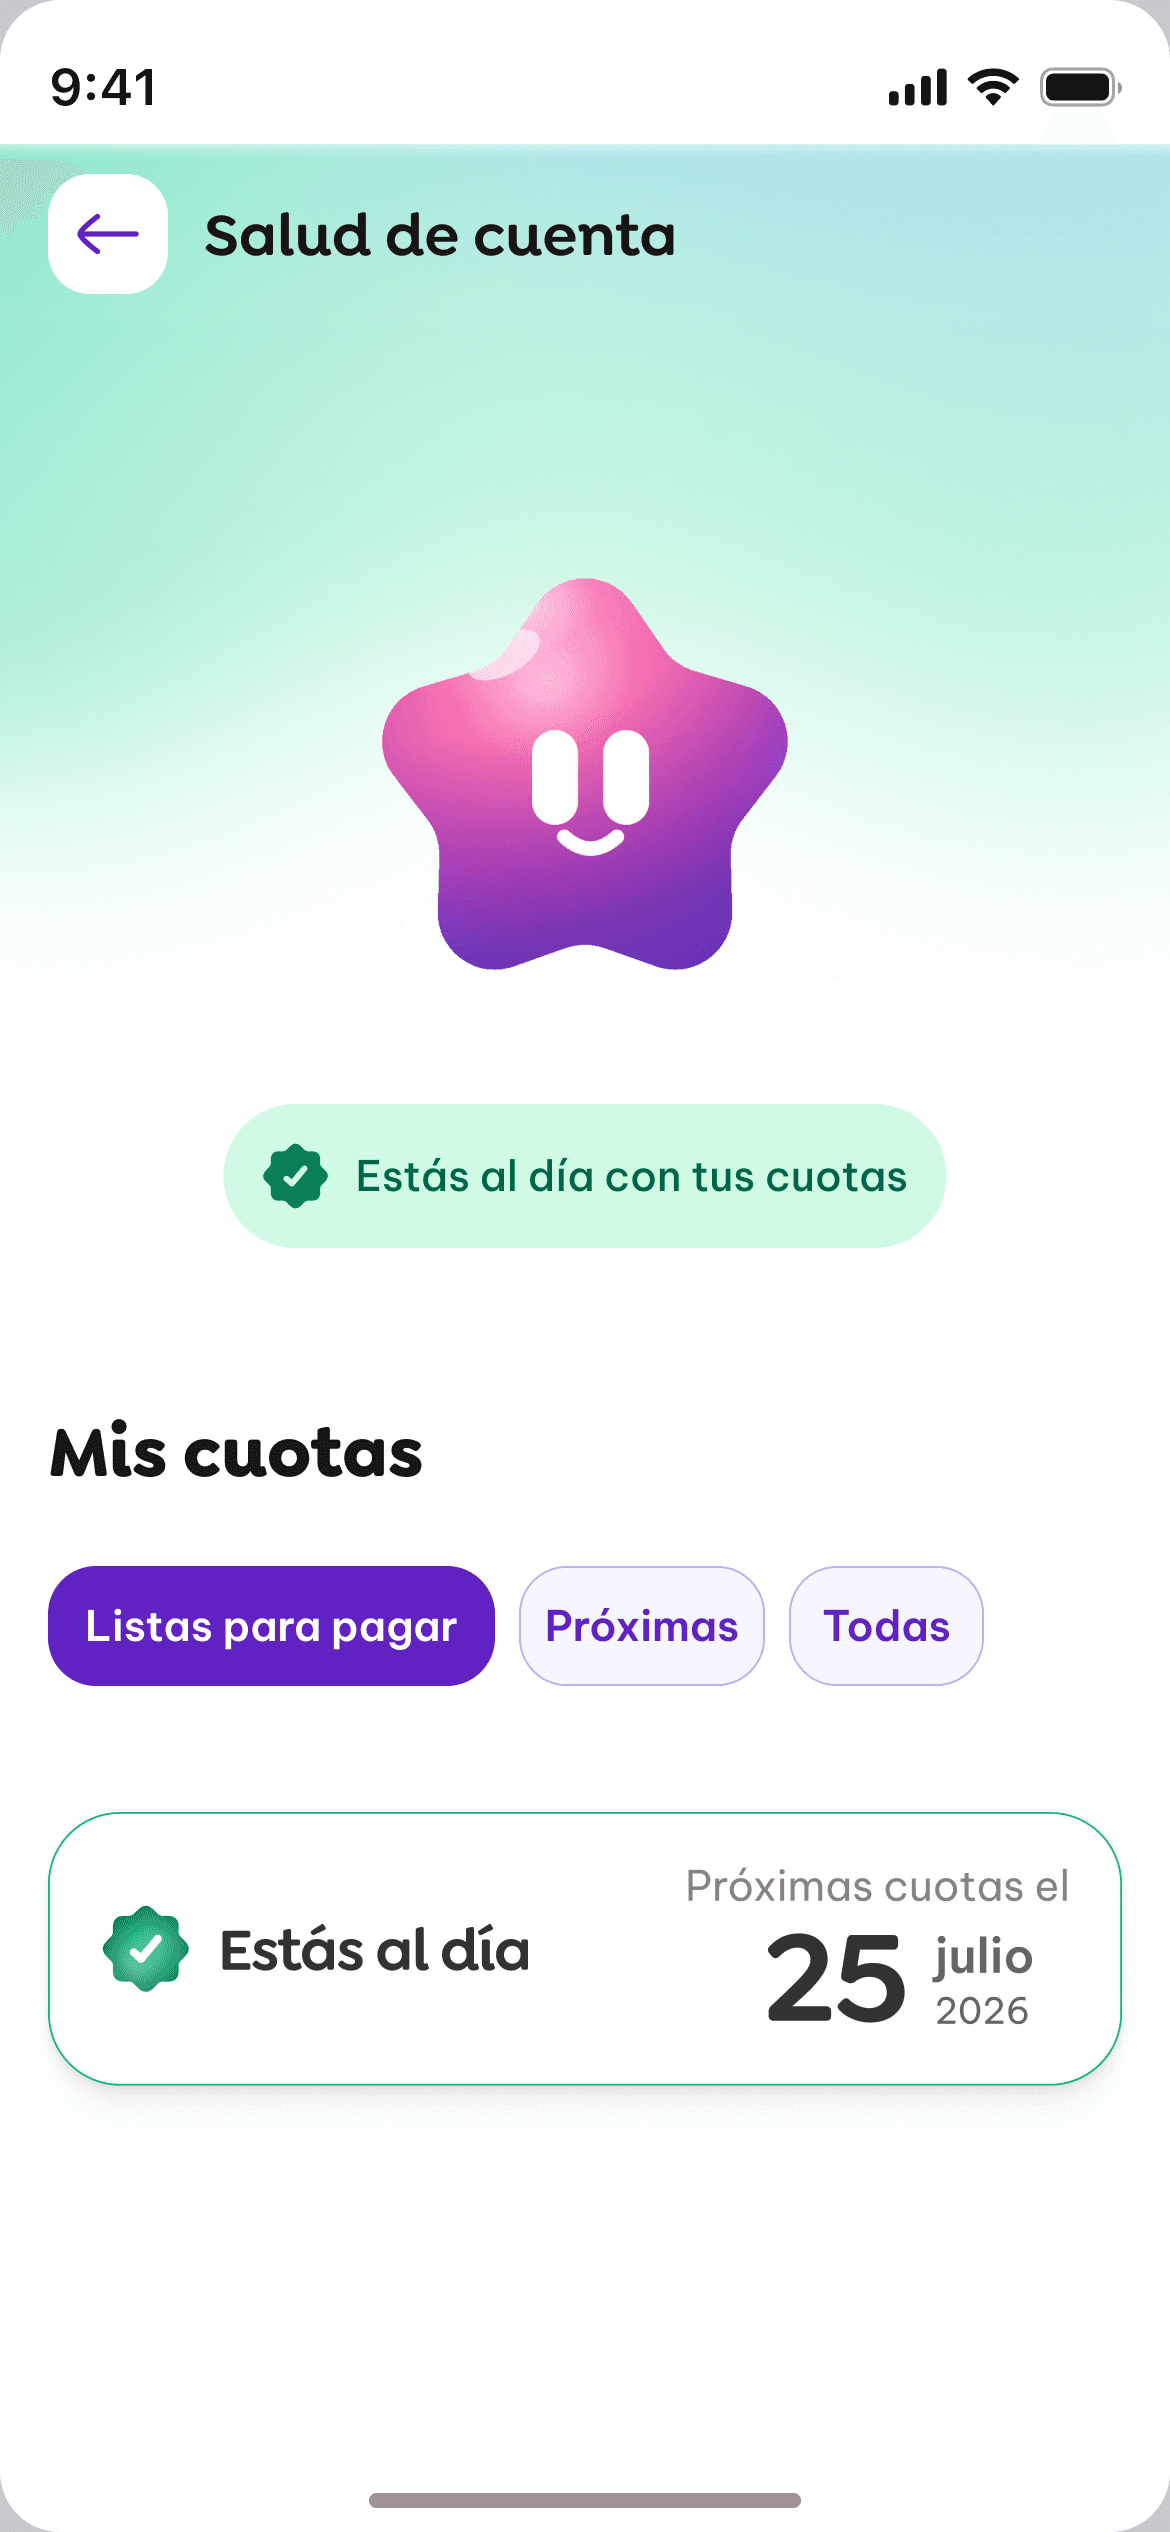
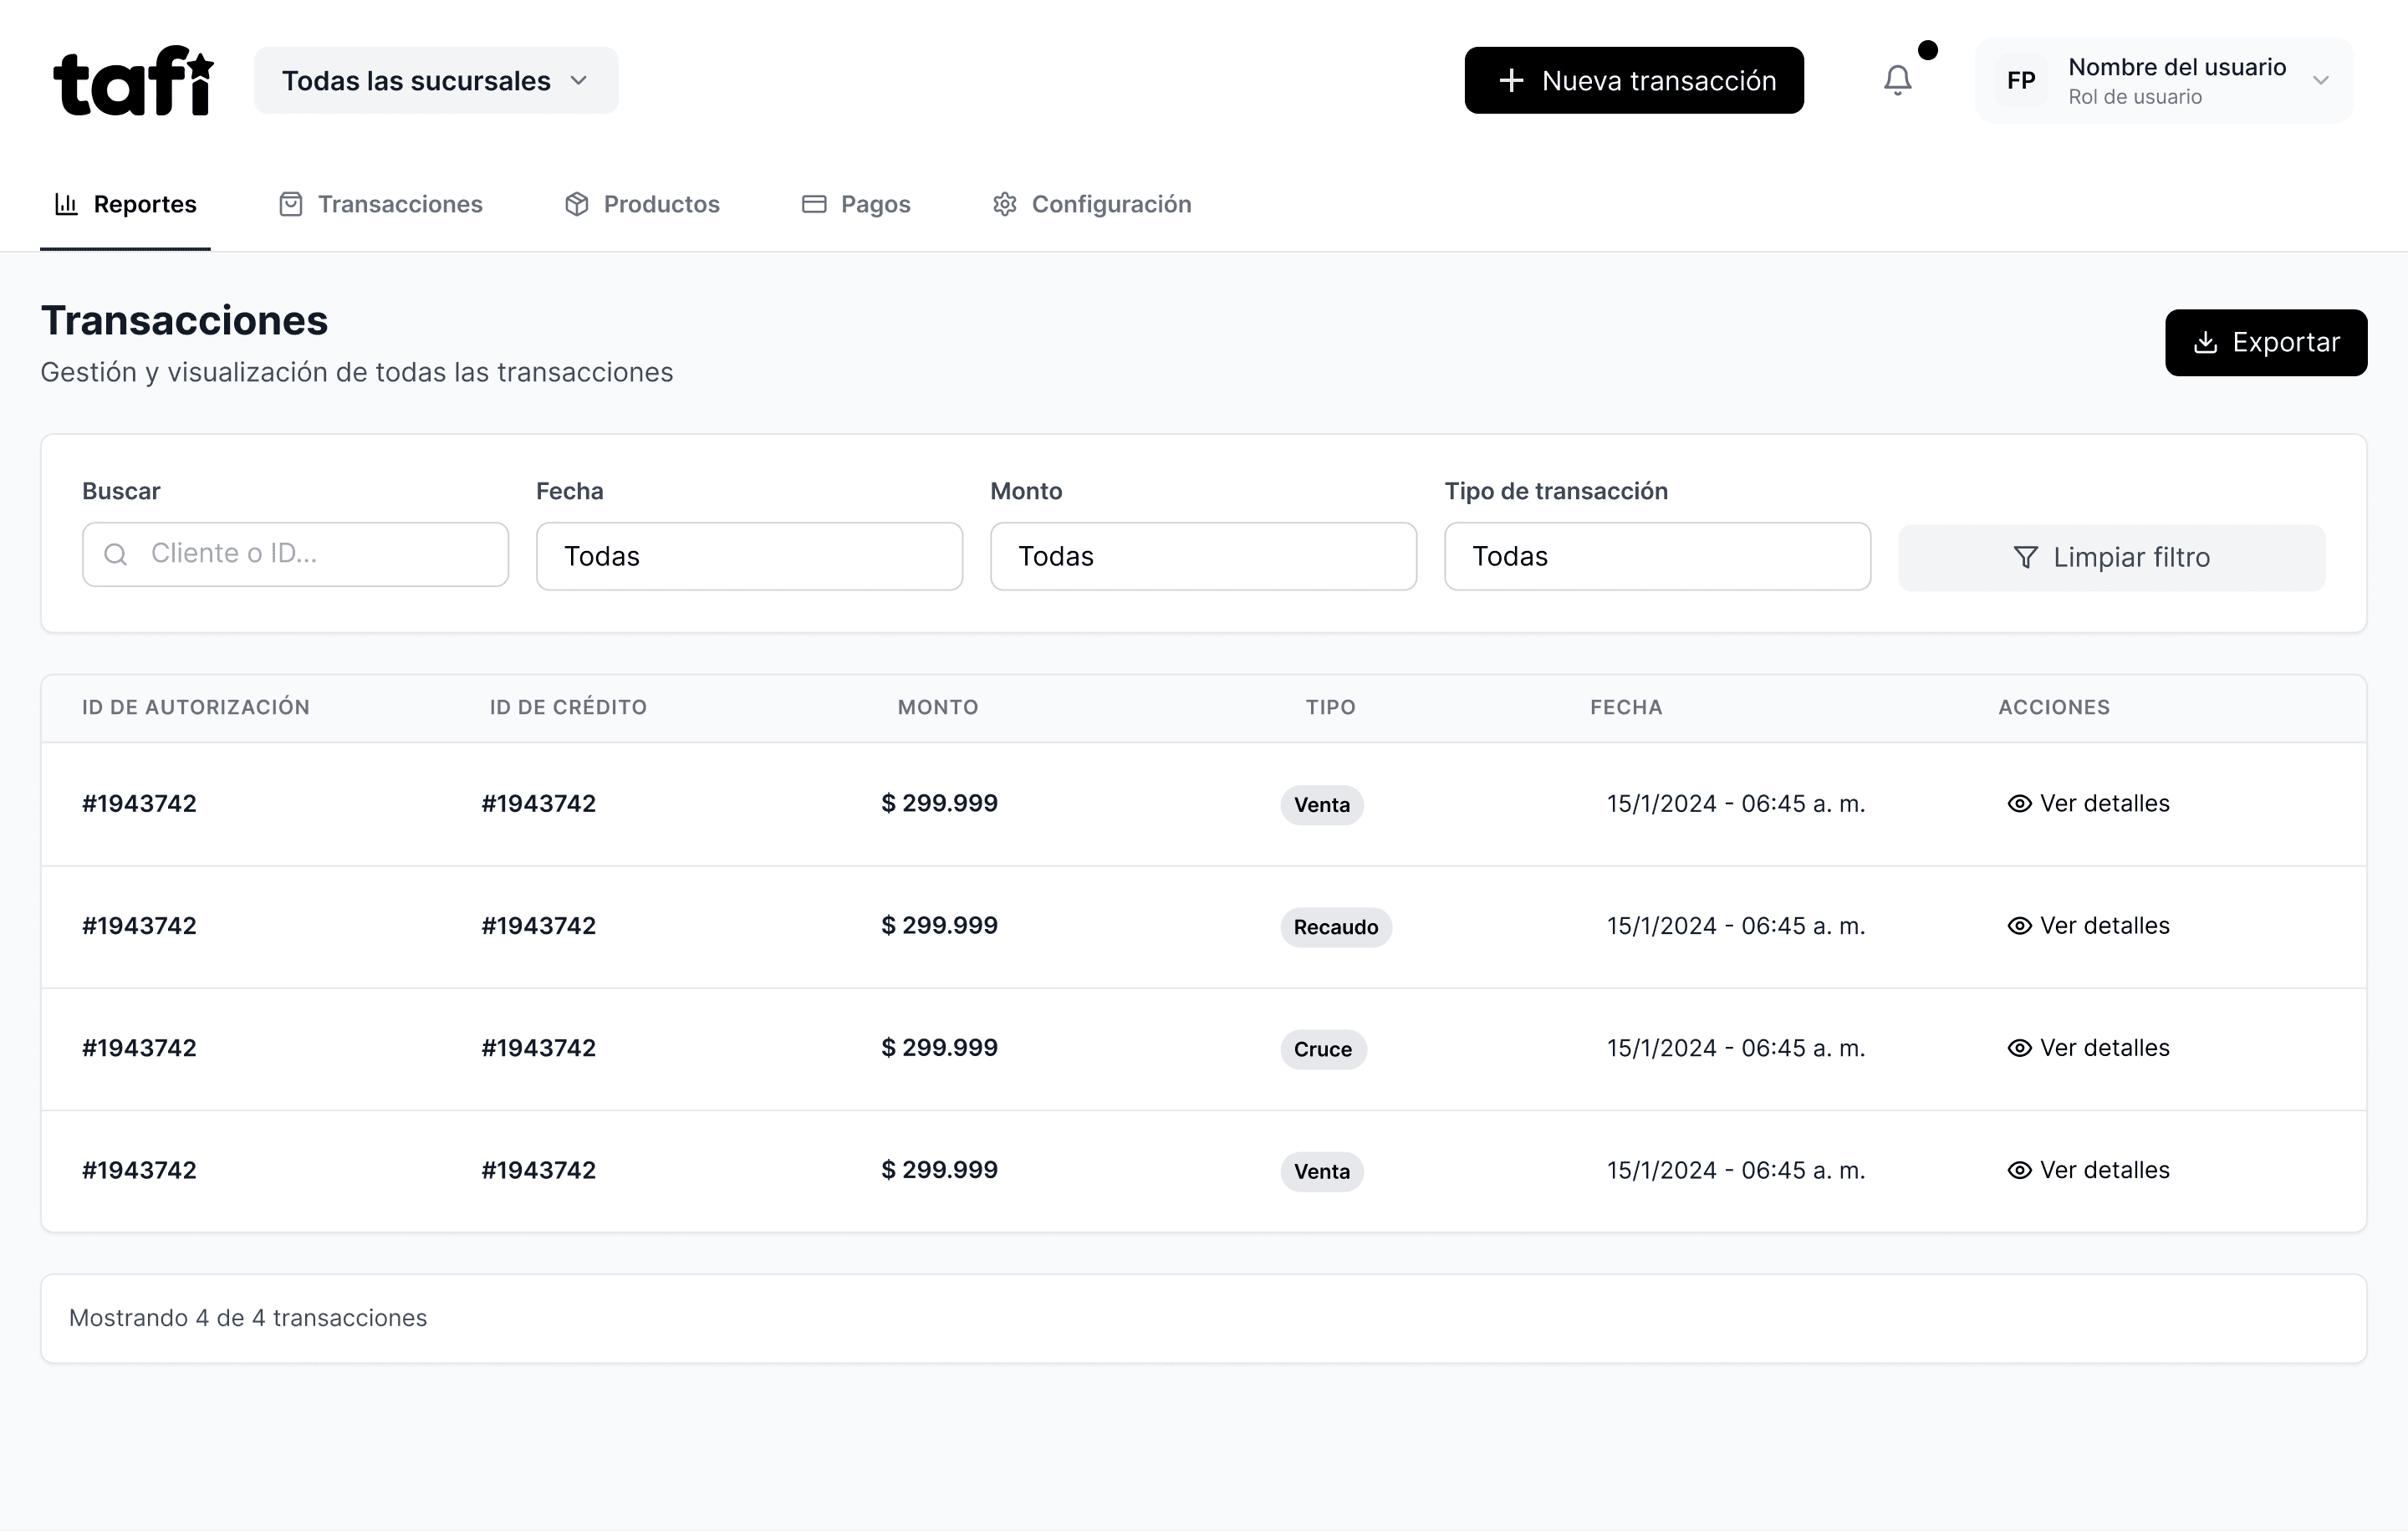
Tafi offers consumer credit in Panama at the merchant counter and over WhatsApp. Its credit core, accounting, collections, identity checks and channels run on Myntex Credit OS today.
Tafi is one implementation. Your operation can use any channel through the API.
Buying on credit
01Purchase request
02Choose a plan
03Credit contract
04Sign with OTP
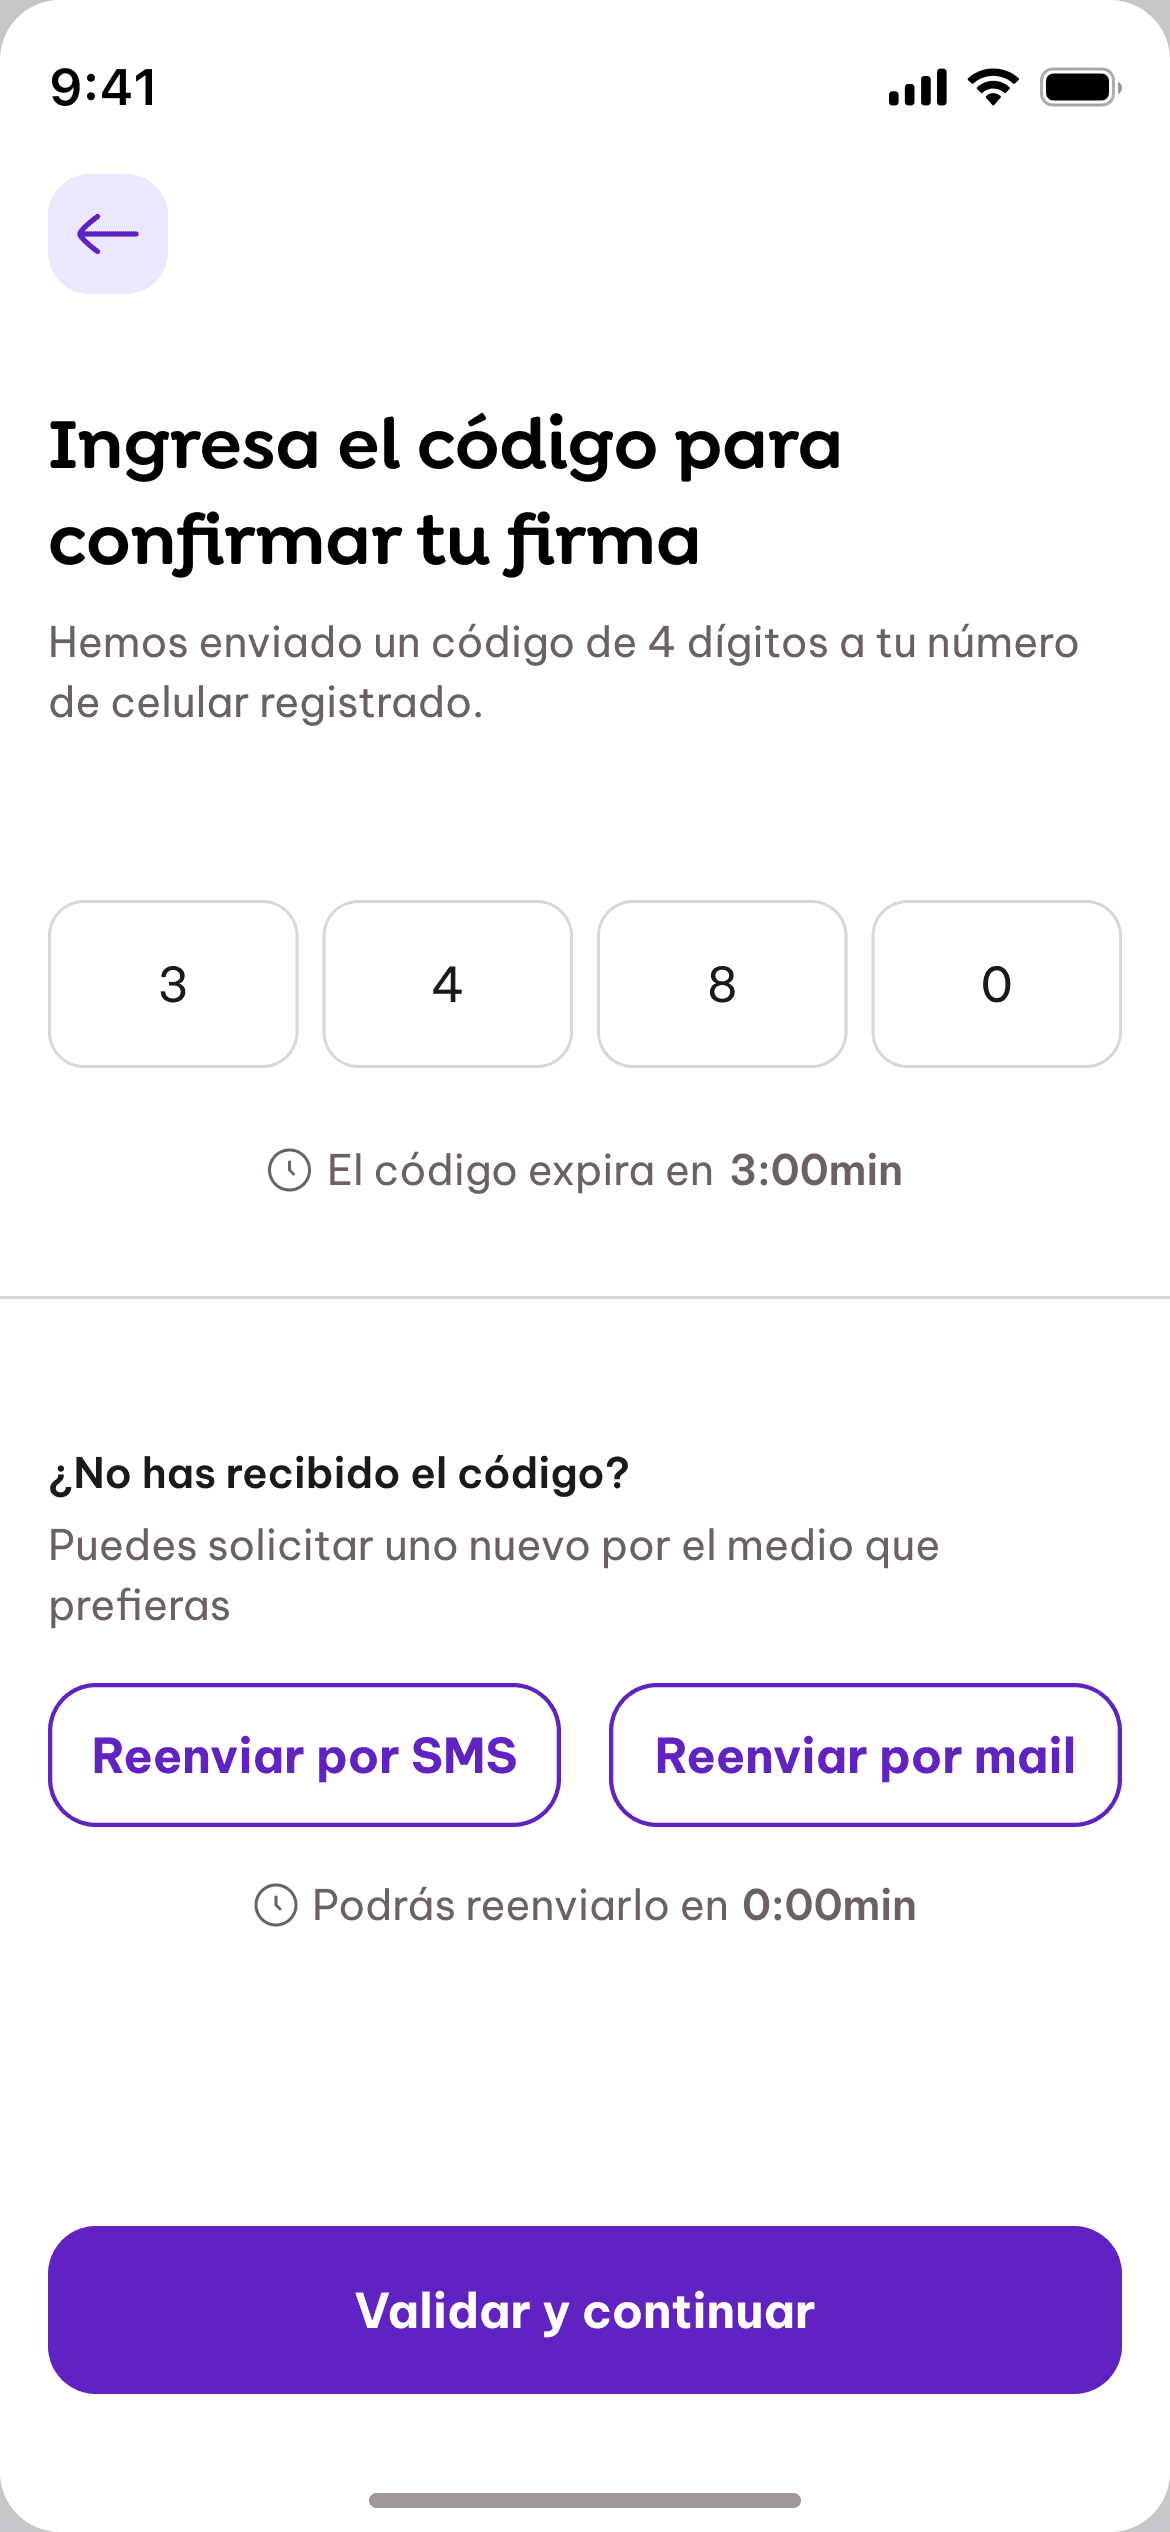
05Identity check
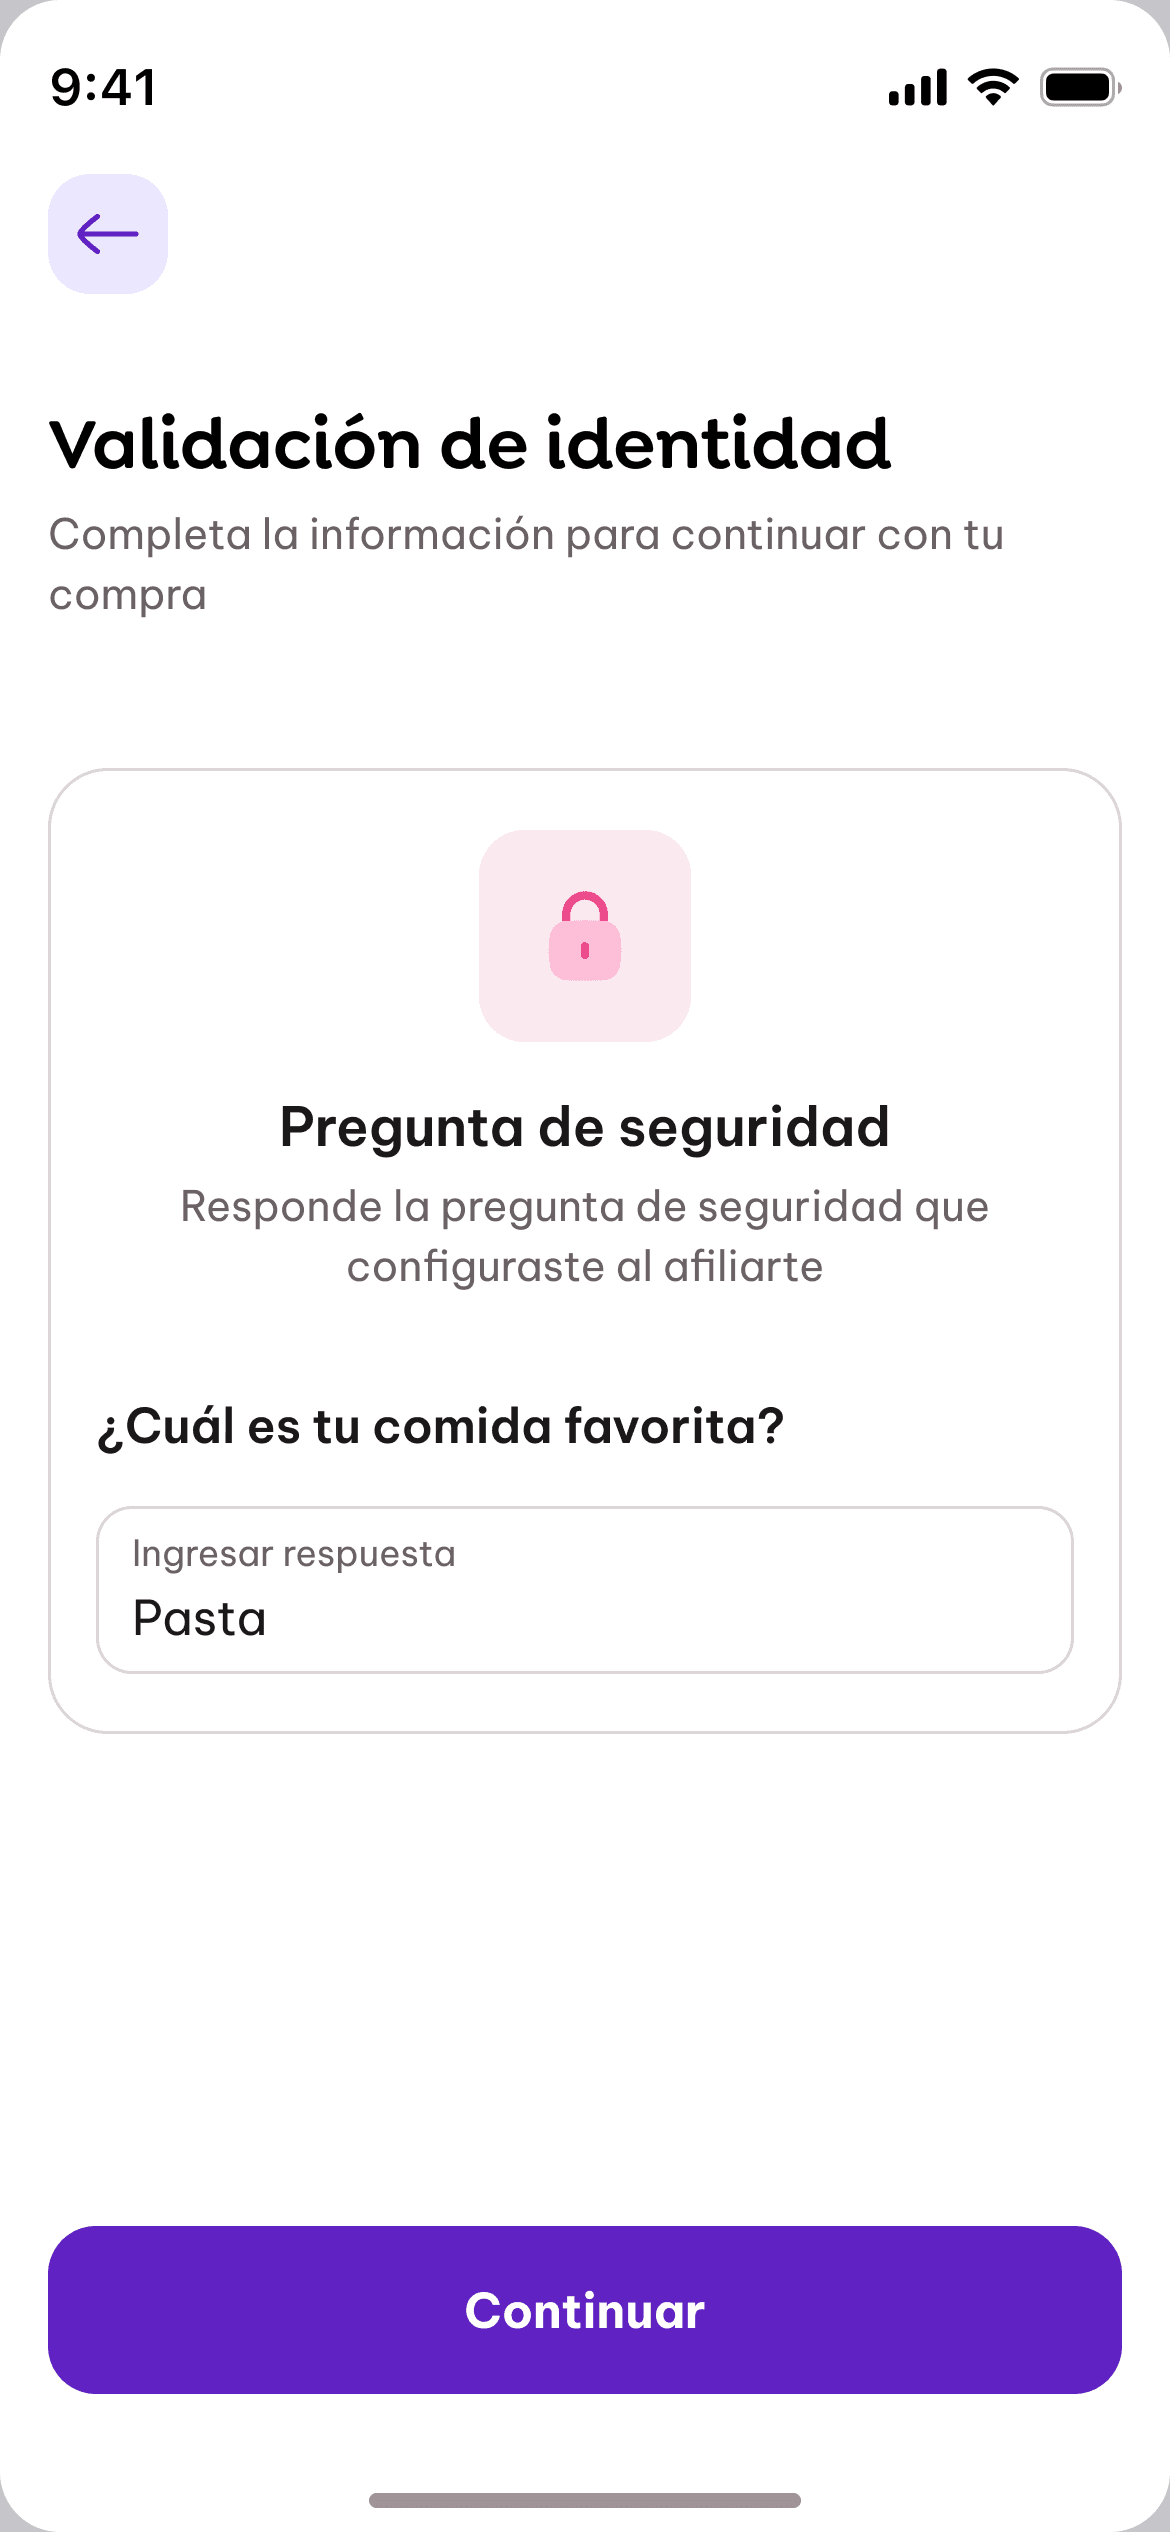
06Approved
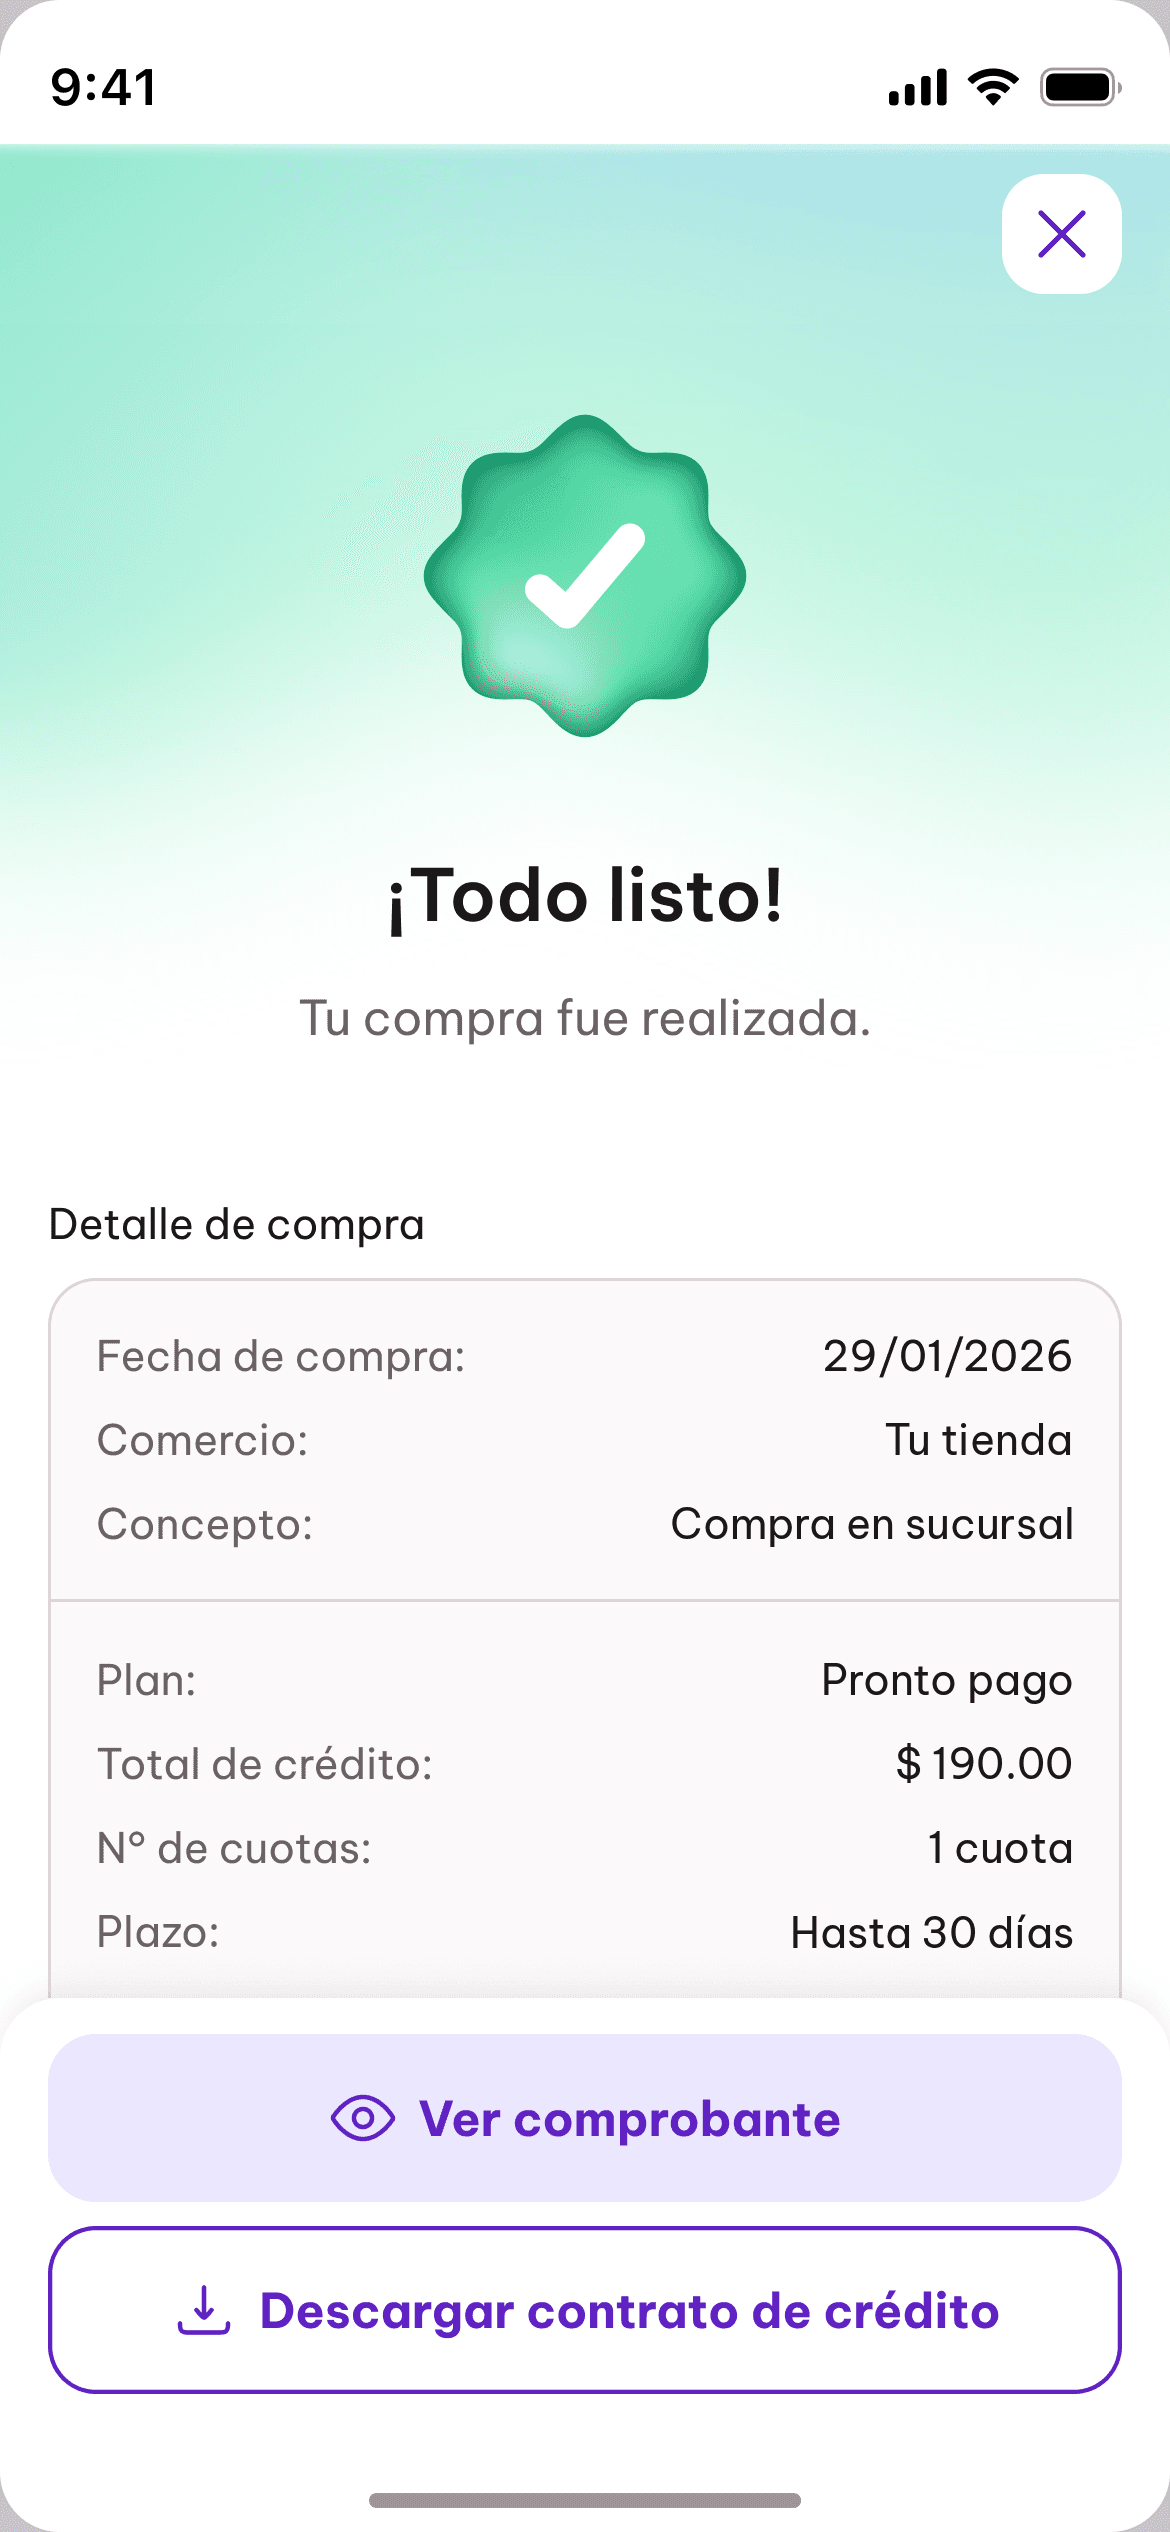
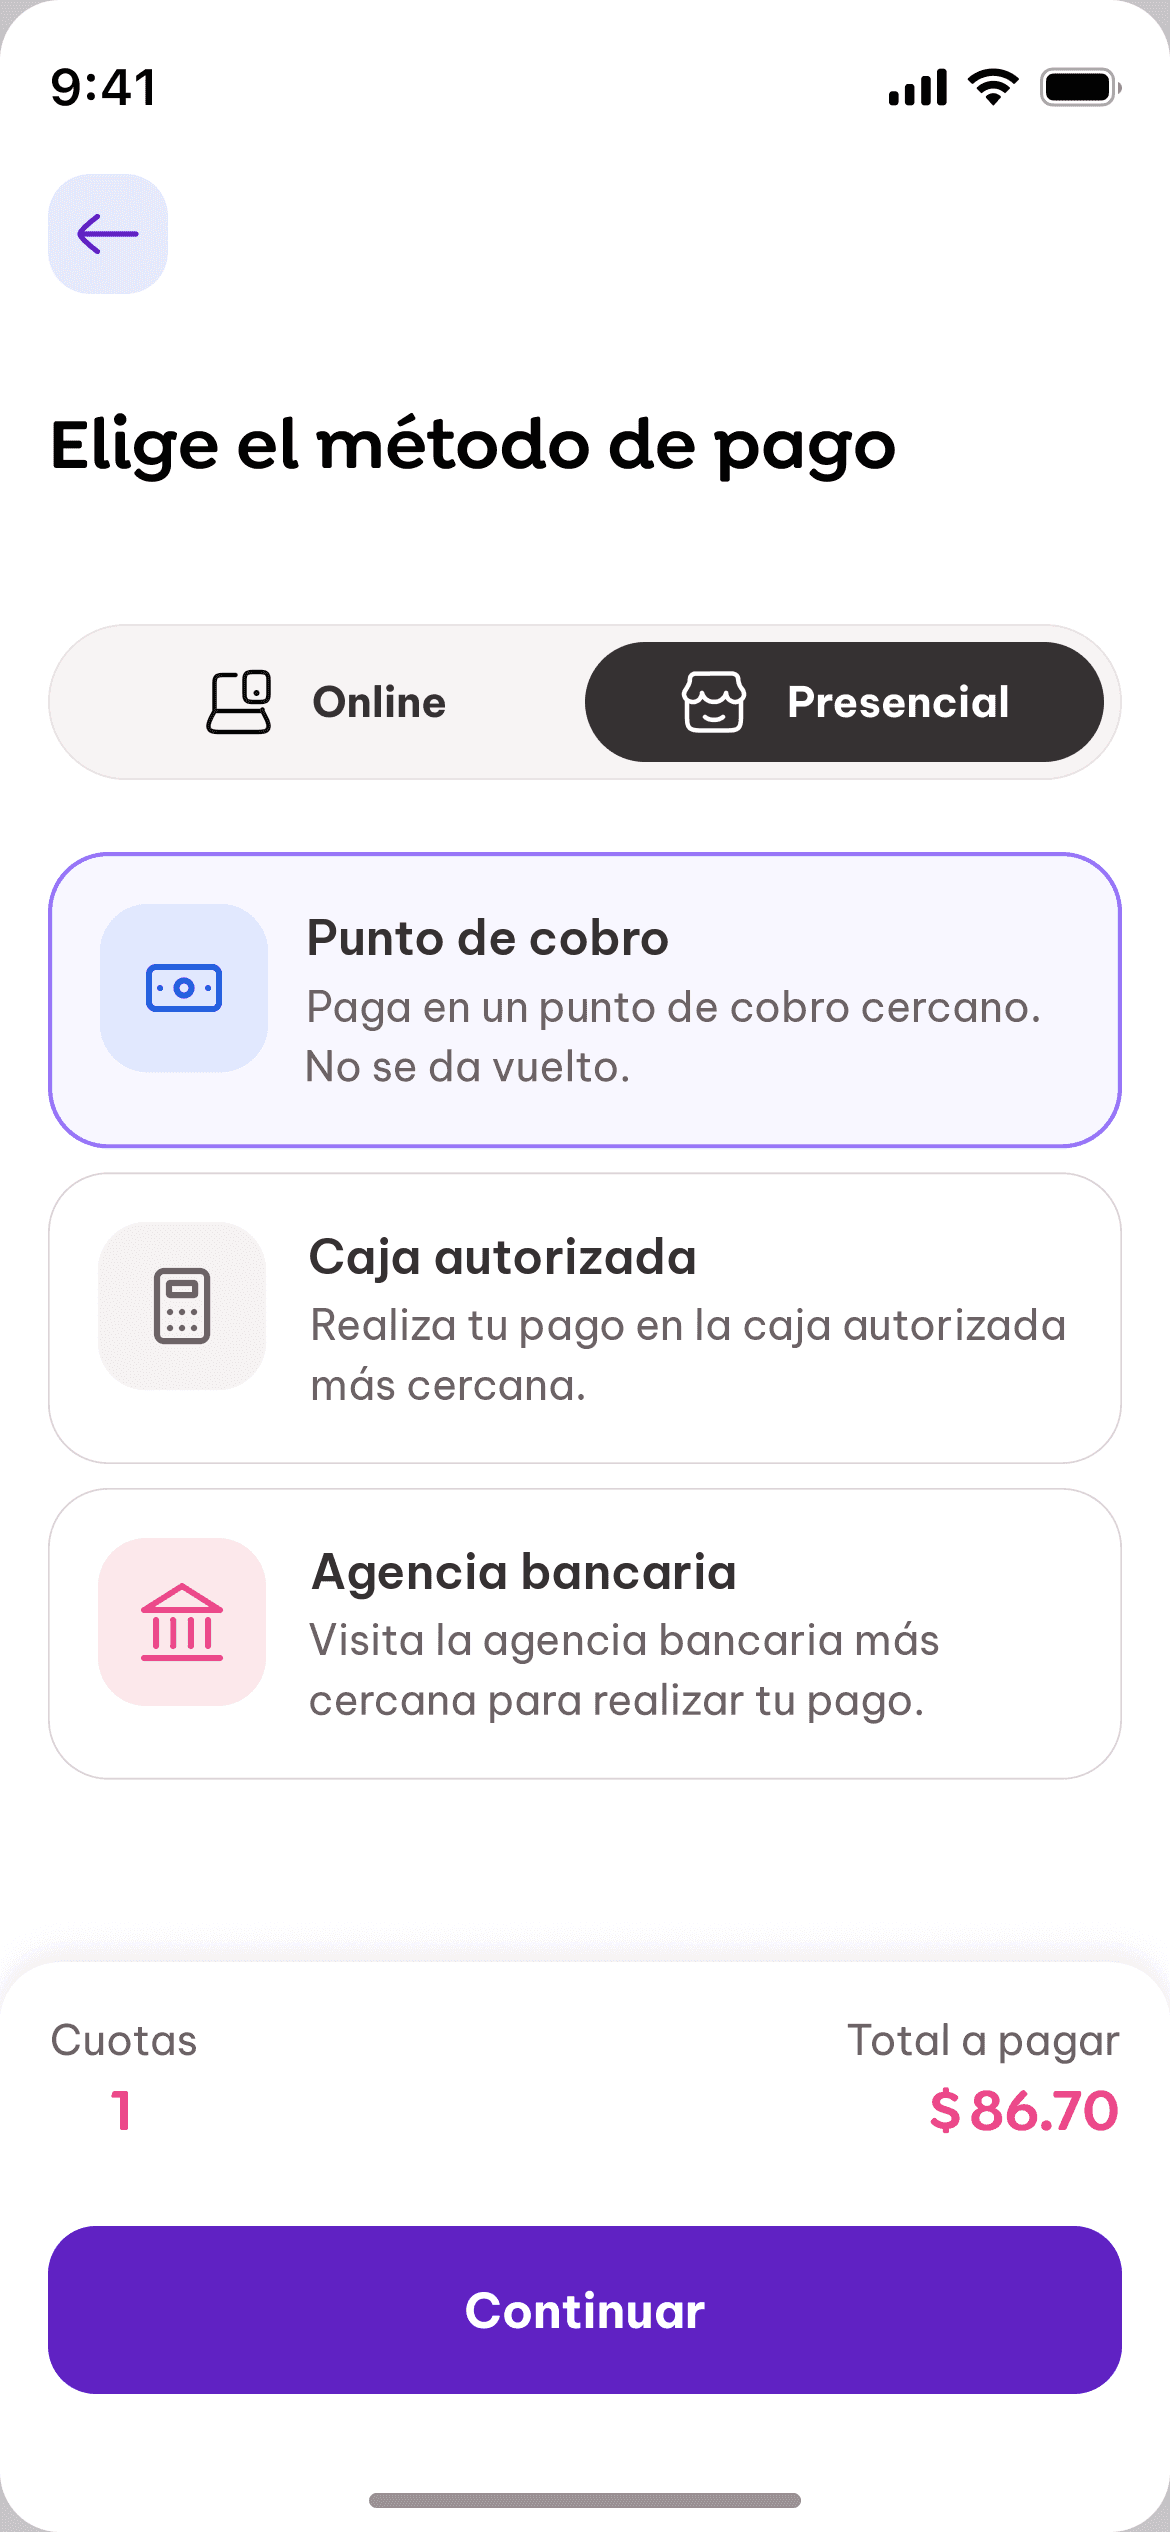
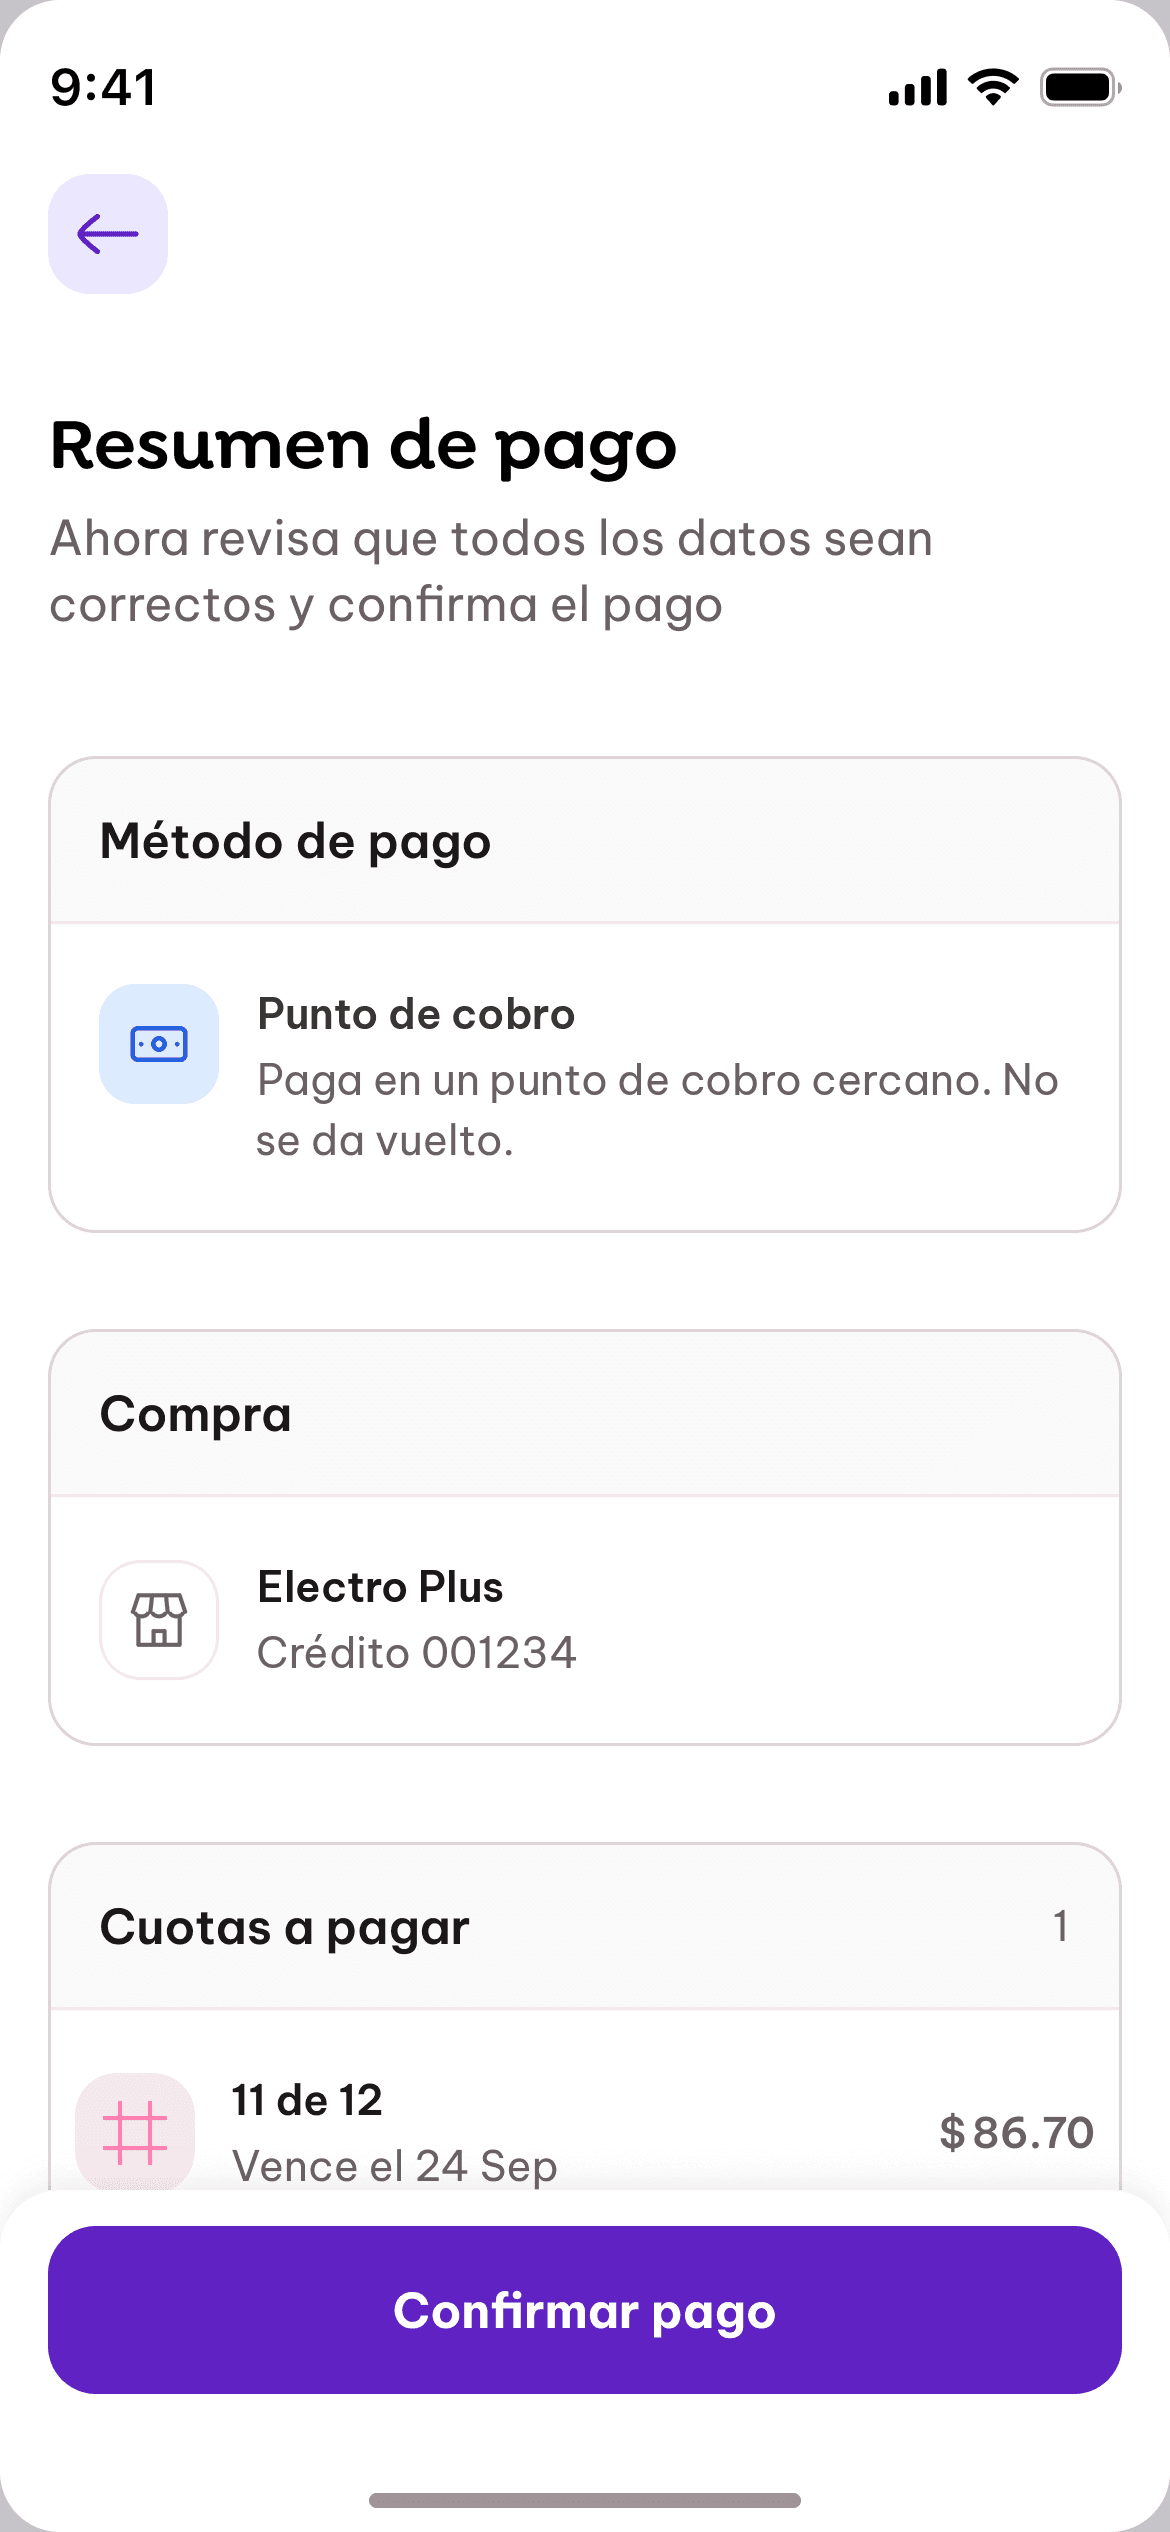
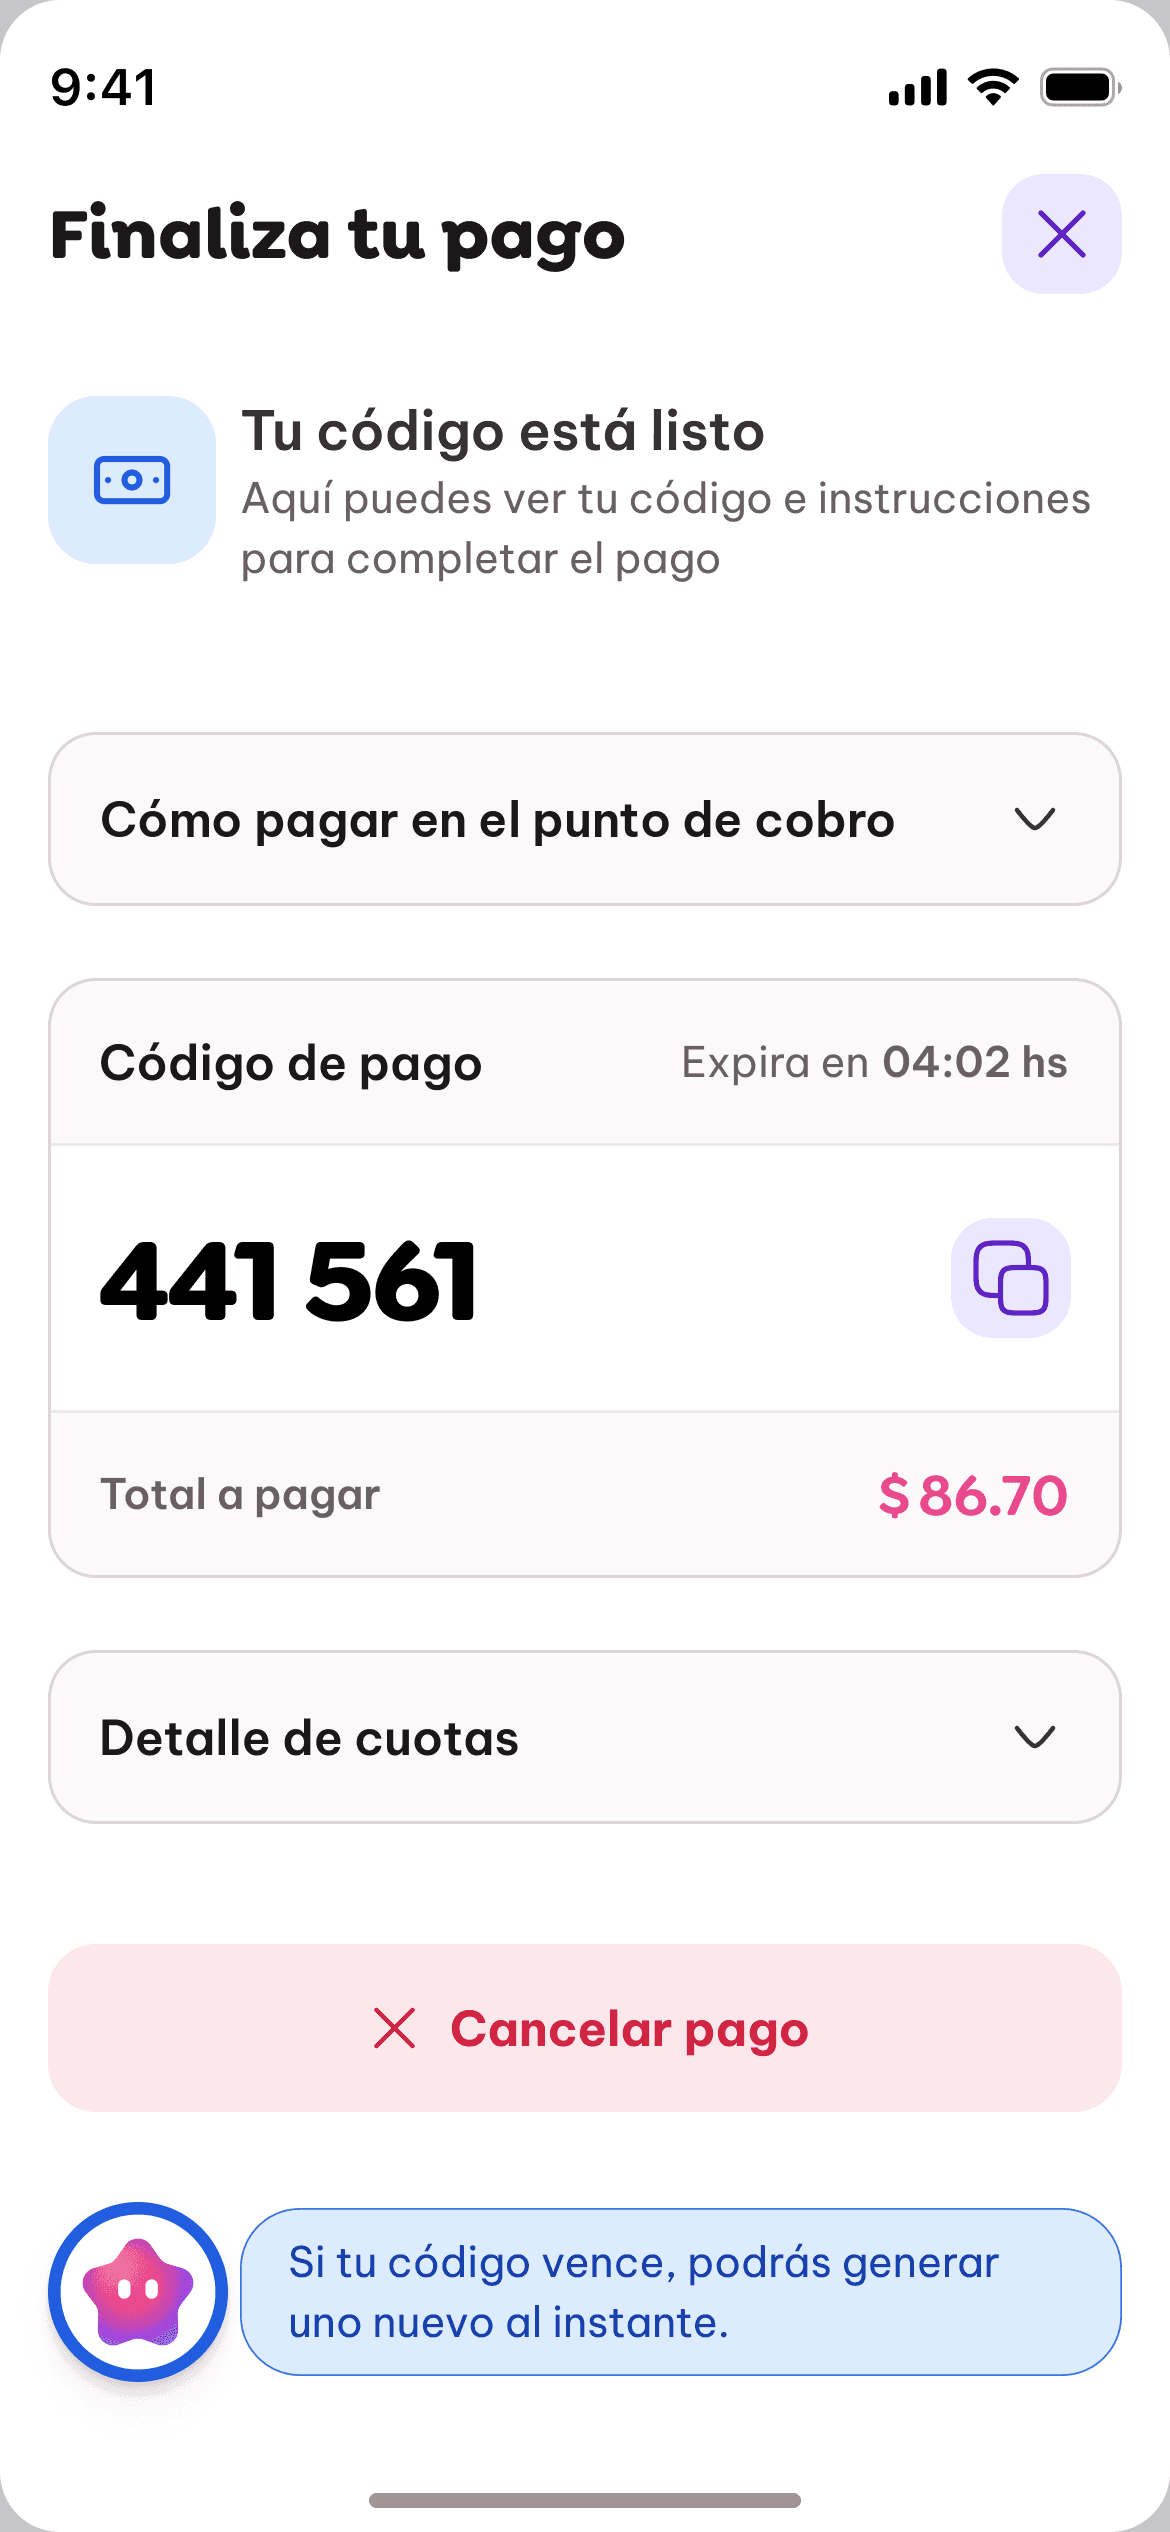
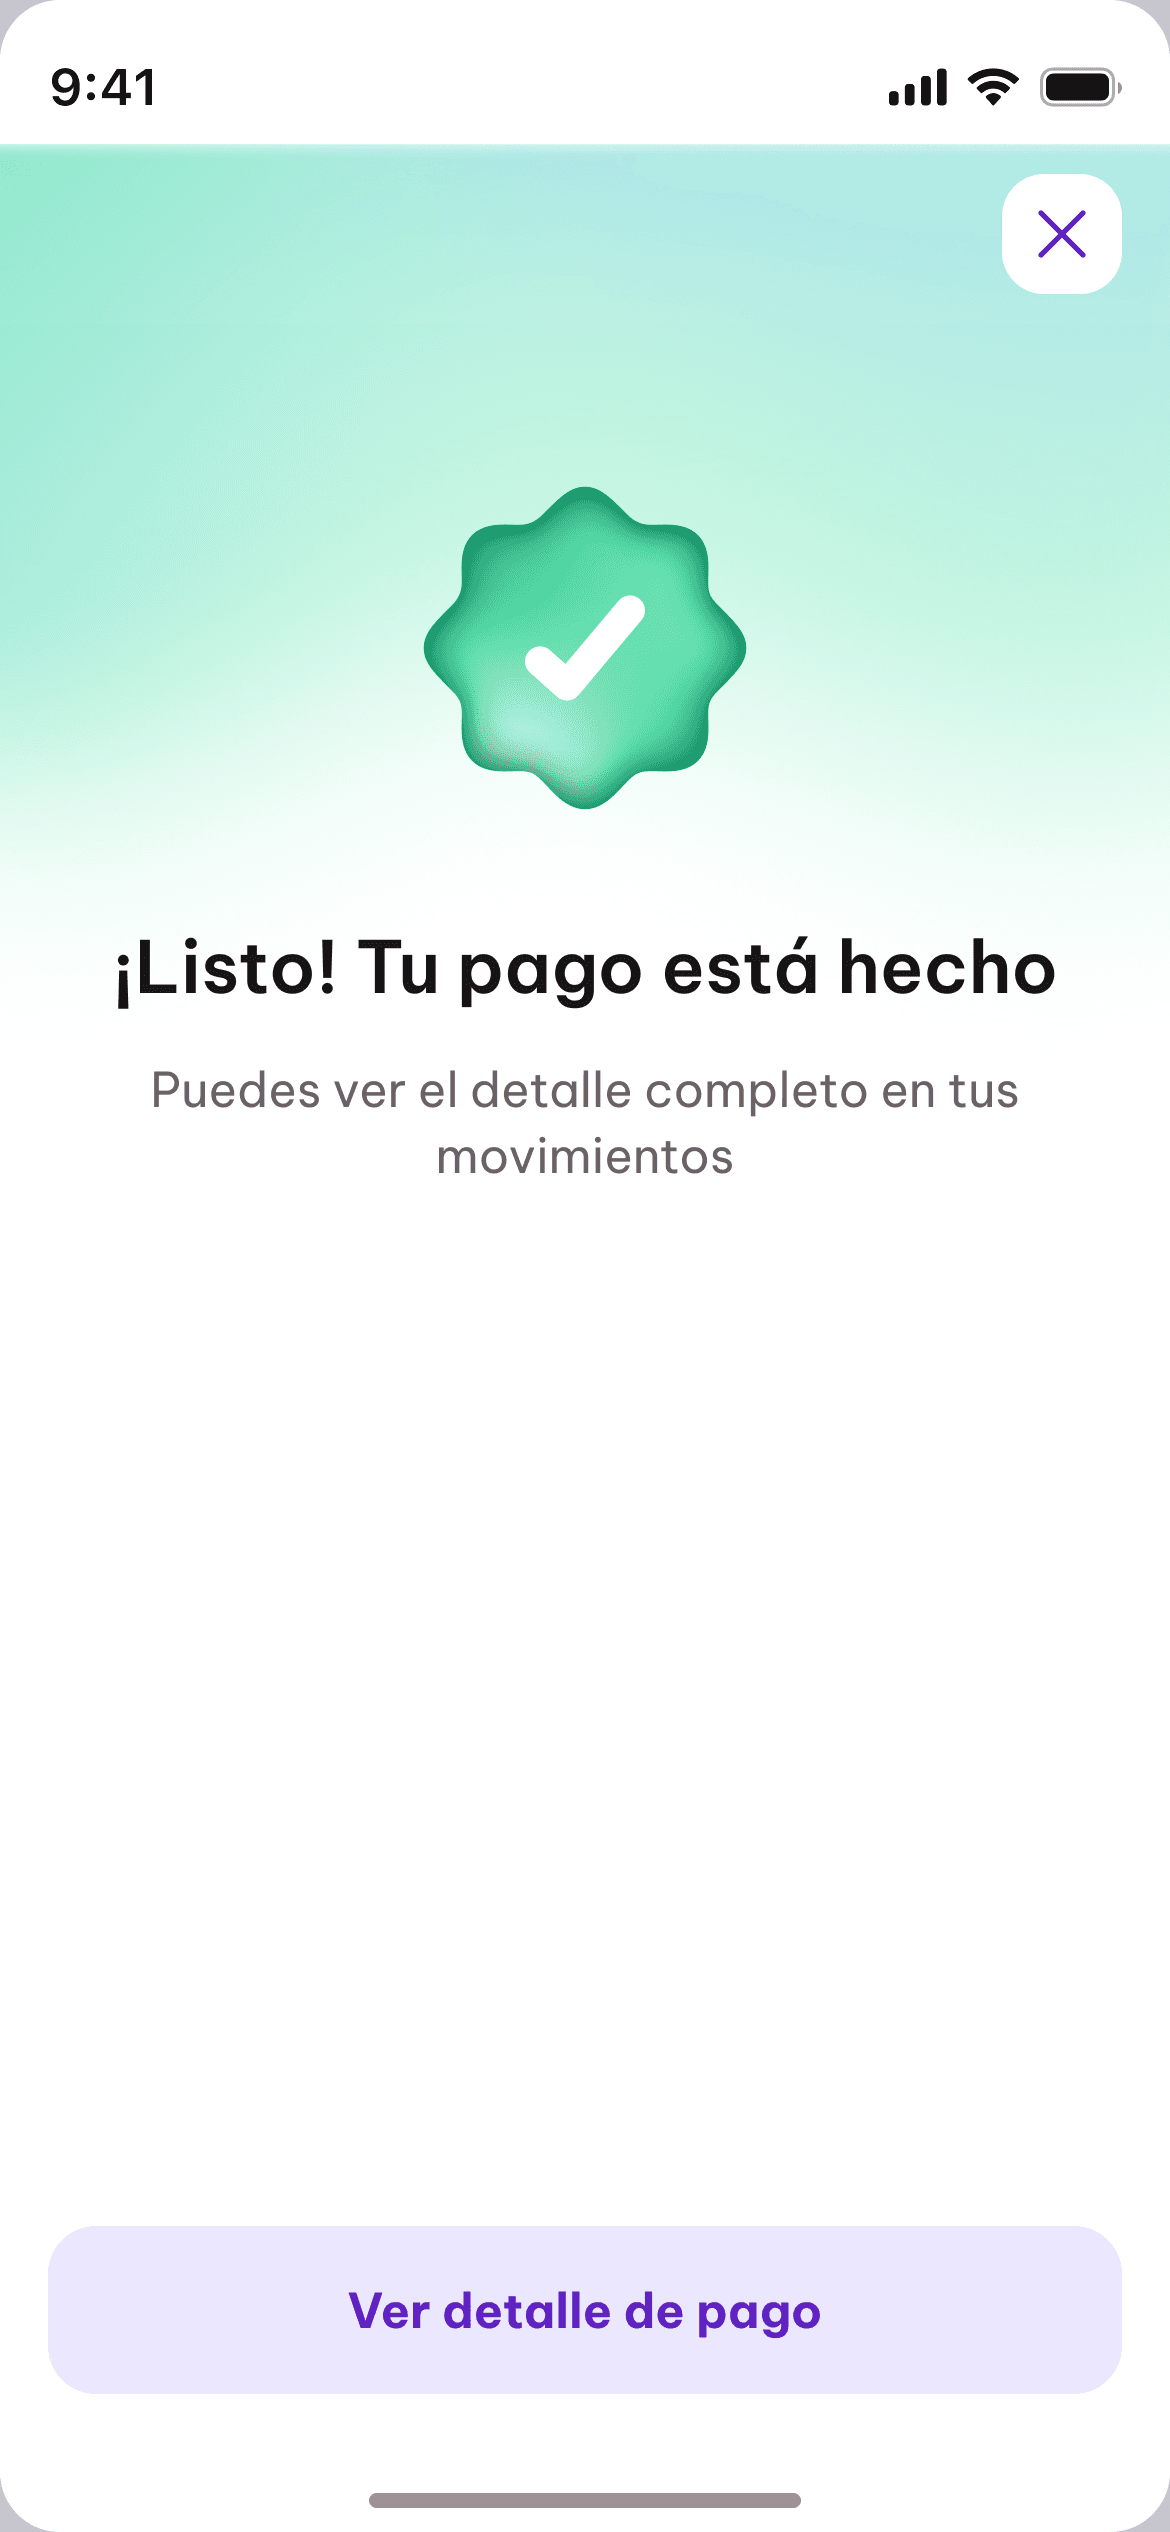
Paying it back
01Choose installments
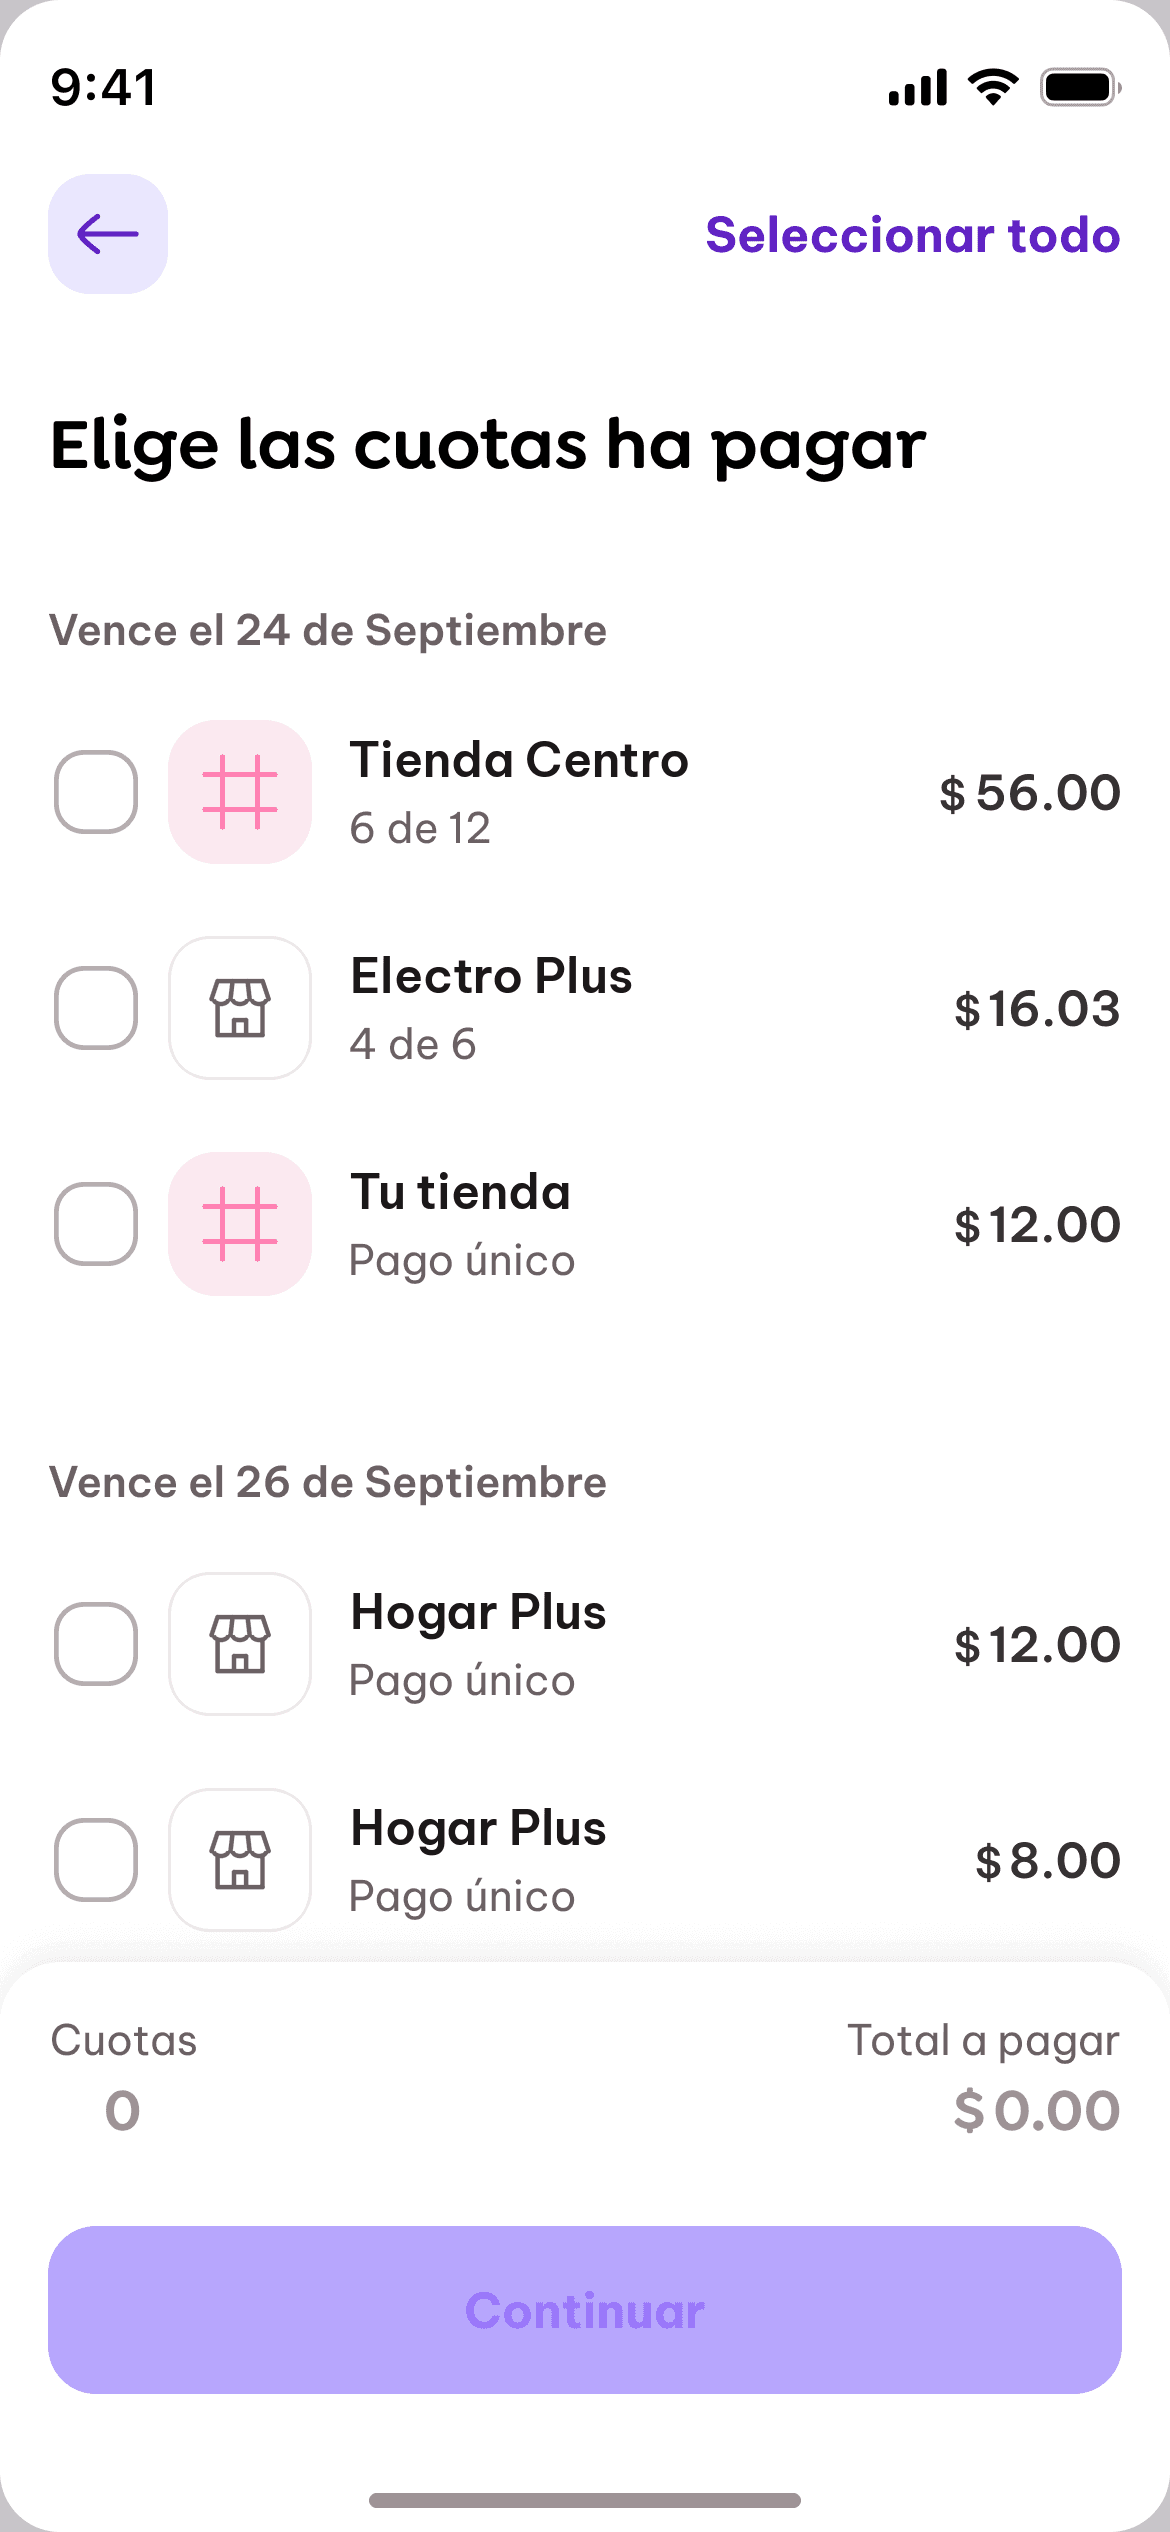
02Payment method
03Payment summary
04Payment code
05Payment success
Around the app
01Welcome
02Home
03Purchases
04Merchants
05Account health
Who it's for
Lending well is no longer a question of size.
Credit unions and lenders
You lend with a system that works but isn't precise. The technology you need exists — it was built for banks.
Missing: technology at your scale
Banks
You have capital, criteria and a license. You need a core that lets you launch a product without a months-long project.
Missing: a core that lets you move
Retailers
You have customers, traffic and the will to sell on credit. What's missing is knowing who to say yes to.
Missing: risk criteria
Fintechs and BNPL
You want to reach the market without first building infrastructure. We've been the buyer: Tafi was exactly where you are.
Missing: time
FAQ
What people ask us before starting.
01Which parts of the credit operation does Myntex cover?
Credit core, decision engine, accounting and collections in one system, with point-of-sale and conversational channels and an identity and compliance layer. On a discovery call we review which ones your operation needs.
02How does it integrate with the systems I already use?
Every module is exposed through APIs and events, so you can modernize in phases: replace the most expensive piece first, keep the systems that still earn their keep, and retire the rest on your schedule. Myntex Connect integrates your core banking, credit bureau, ERP and channels along the way.
03How do you handle compliance and AML?
Identity checks, AML list screening, the customer risk matrix and credit policy run inside the same flow as the loan. Every client is scored on six risk factors with a resulting risk level, the SBP client reports come from the same model, and we ingest 24 official sanctions, PEP and high-risk-jurisdiction sources with row-level lineage.
04What does forward-deployed mean in practice?
Myntex engineers join your team for the implementation and work with your risk, operations and technology people until you place your first loan. After that, Myntex Review reports back on your portfolio every month.
05How does an implementation start?
With Myntex Proof: we show the system running on a real credit operation and how it was measured. Then Setup configures your products and Connect integrates your systems.
06What can I configure?
Your installment credit products, decision policies, scoring rules and integrations. Implementation is configuration-driven: products and policies are parameters.
07How do I book a discovery call?
Use the Book a discovery call button and pick a time. Tell us what you want to lend and to whom, and we'll come prepared.
Myntex. Your credit, up and running.
Tell us what you want to lend and to whom. We'll show you how it can work.